Loading article...
October 1, 2026
Pension Finance Update September 2026
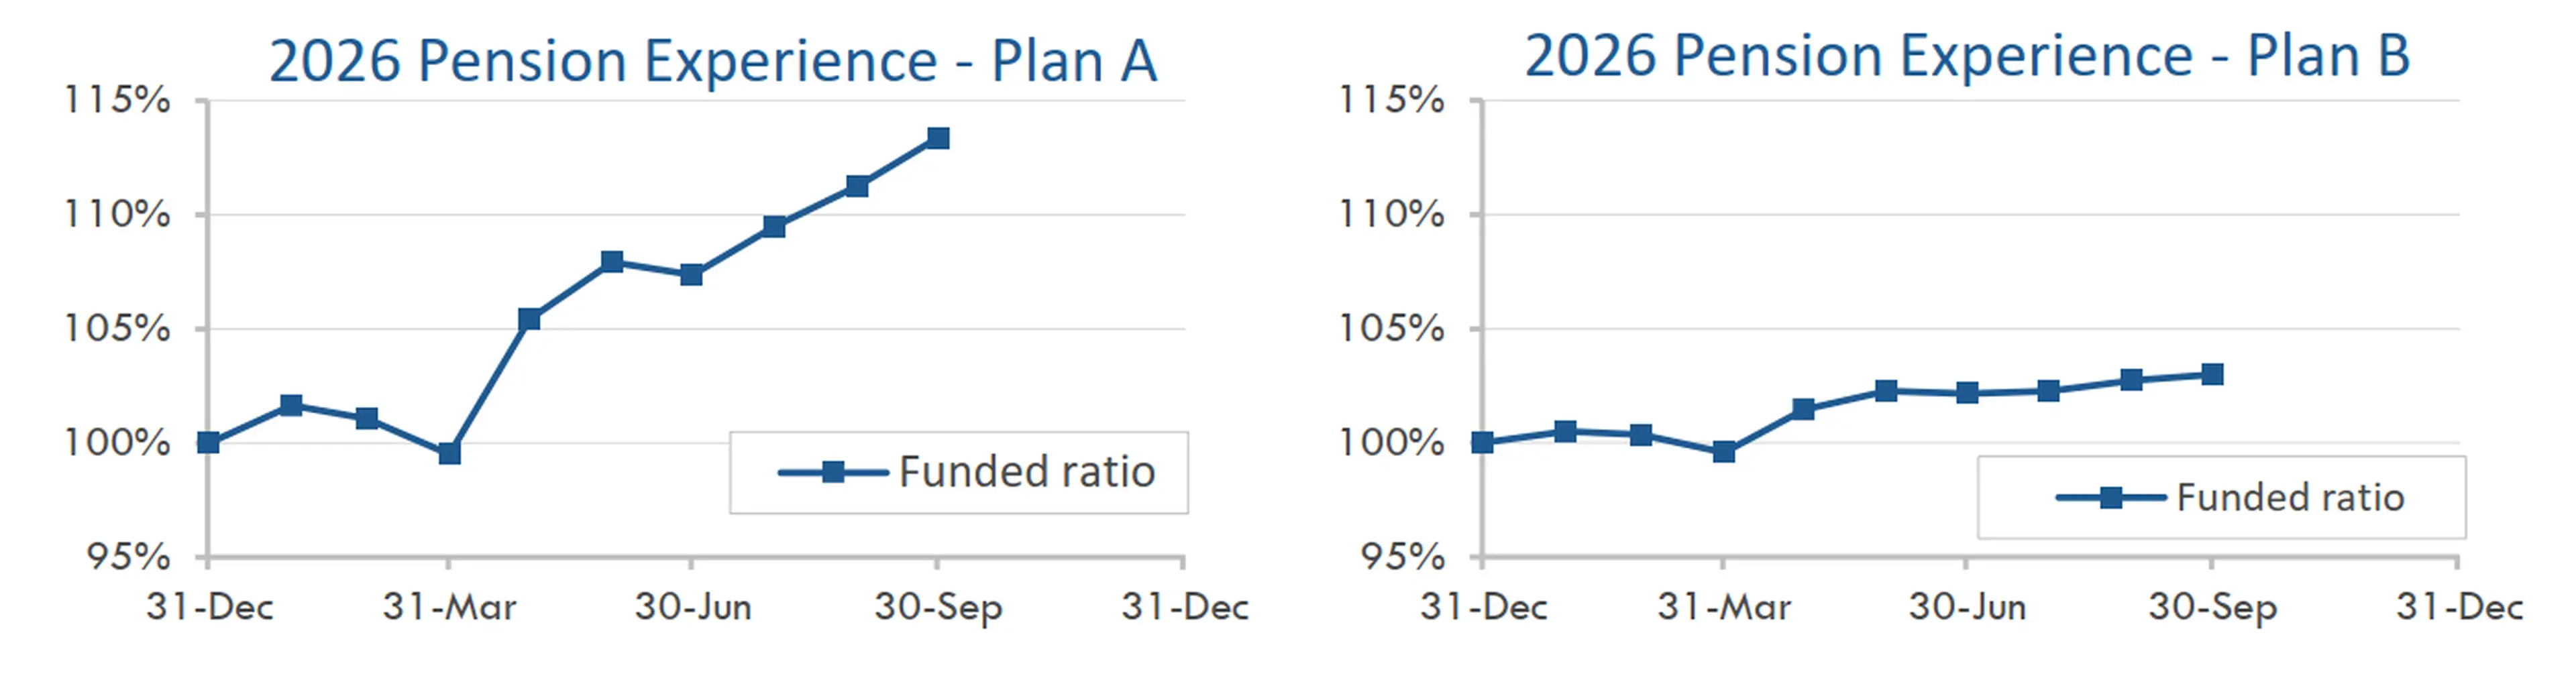
Pension finances improved again during September, driven by higher interest rates, with Treasury yields reaching their highest levels in over 24 years (since June 2002). Both model plans we track1 gained ground during September: Plan A improved more than 2% last month, and is now up 13% for the year, while the more conservative Plan B gained a fraction of 1% during September and is now up 3% through the first three quarters of 2026:
Assets
Stocks (apart from tech) lost ground in September. A diversified stock portfolio lost more than 1% last month but remains up more than 13% through the first three quarters of 2026.
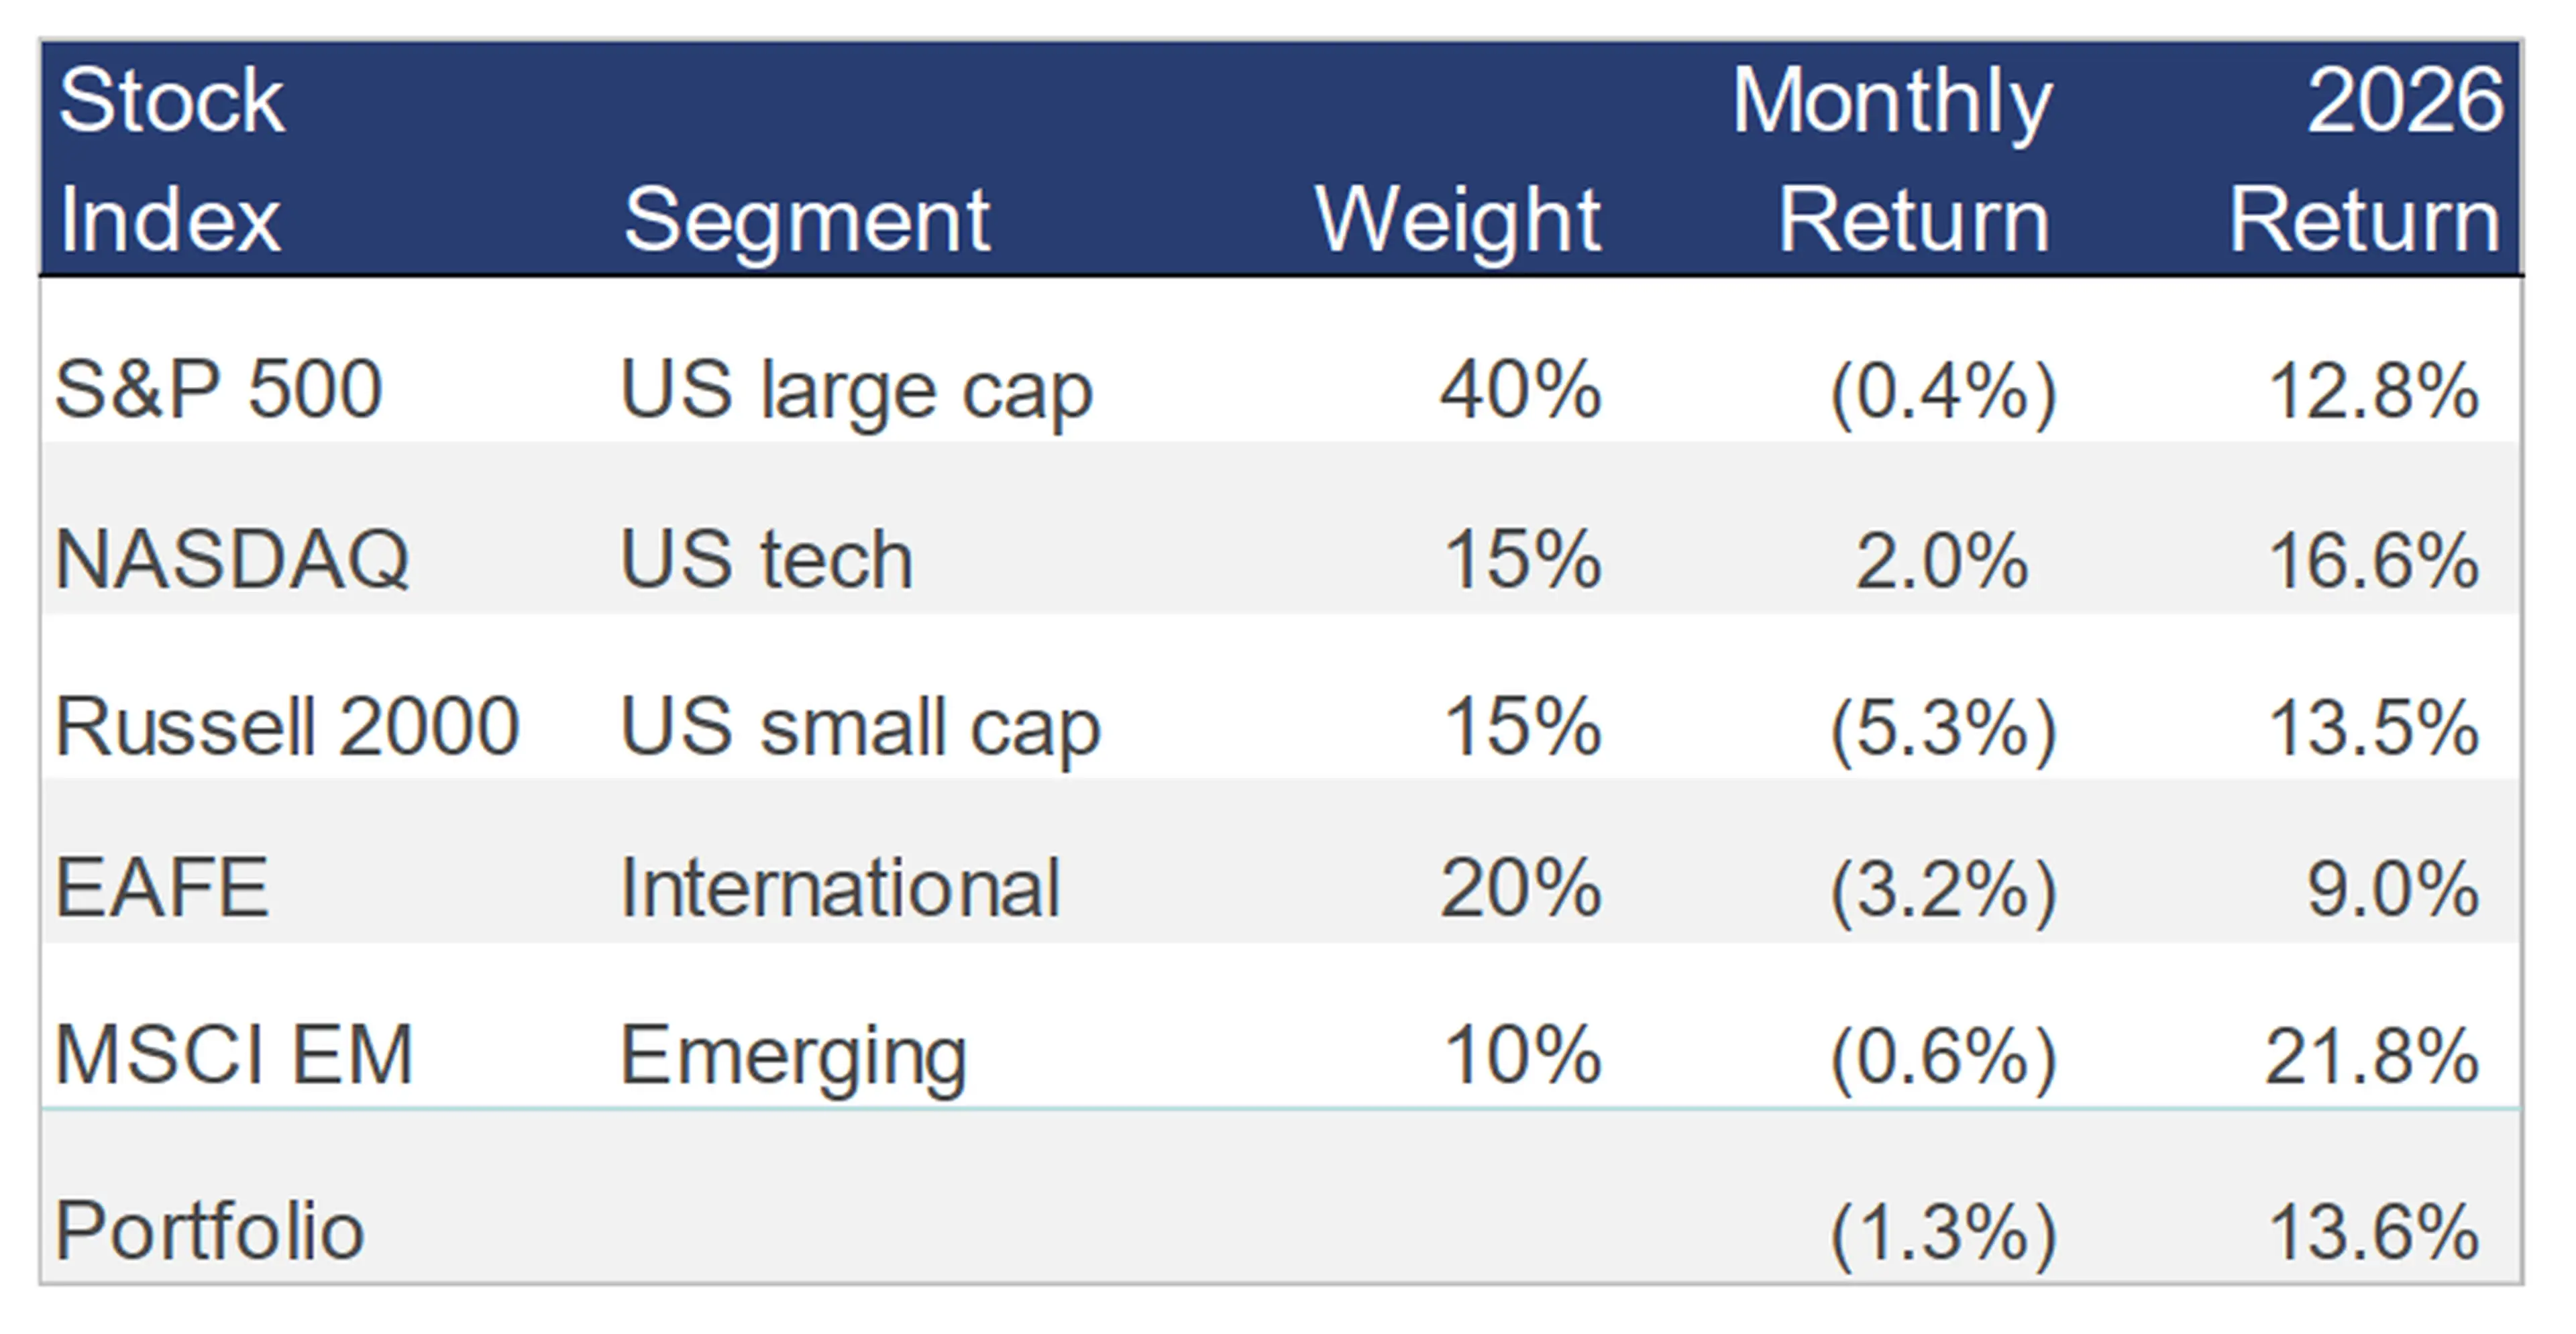
Interest rates spiked up 0.4% last month. As a result, bonds lost 2%-5%, ending September down 3%-7% for the year, with long-duration bonds faring worst.
Overall, our traditional 60/40 lost 2% last month but remains up 6% for the year through September, while the conservative 20/80 portfolio lost more than 2% last month and is now down more than 1% through the first three quarters of 2026.
Liabilities
Pension liabilities (for funding, accounting, and de-risking purposes) are driven by market interest rates. The first graph below compares our Aa GAAP spot yield curve on December 31, 2025 and September 30, 2026 (along with the movement in the curve last month). The second graph below shows our estimate of movements in effective GAAP discount rates for pension obligations of various duration during 2026:
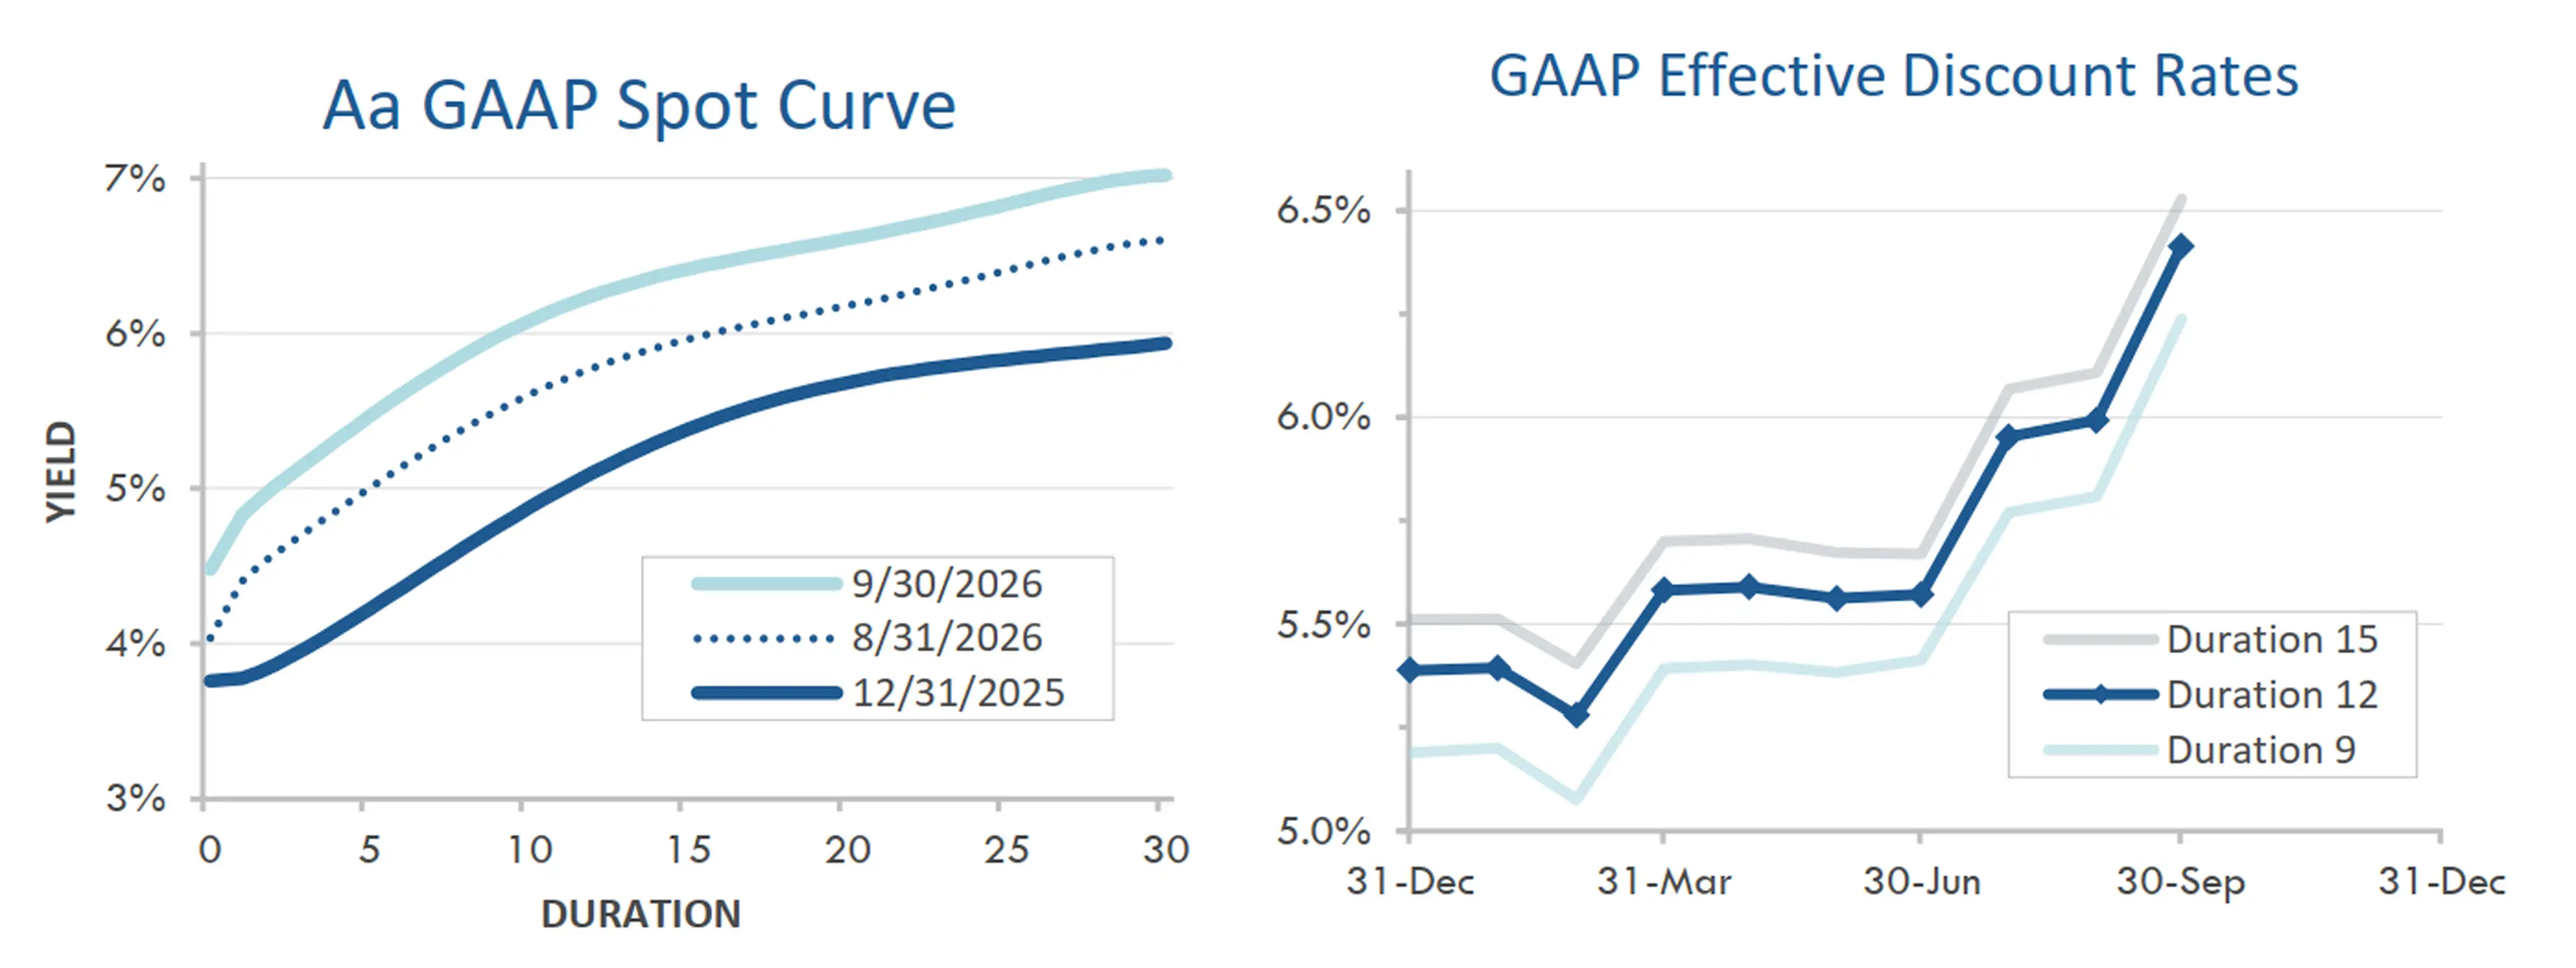
Corporate bond yields rose almost 0.5% in September. As a result, pension liabilities fell 3%-5% last month and are now down 4%-8% for the year through September, with long-duration plans seeing the largest decreases.
Summary
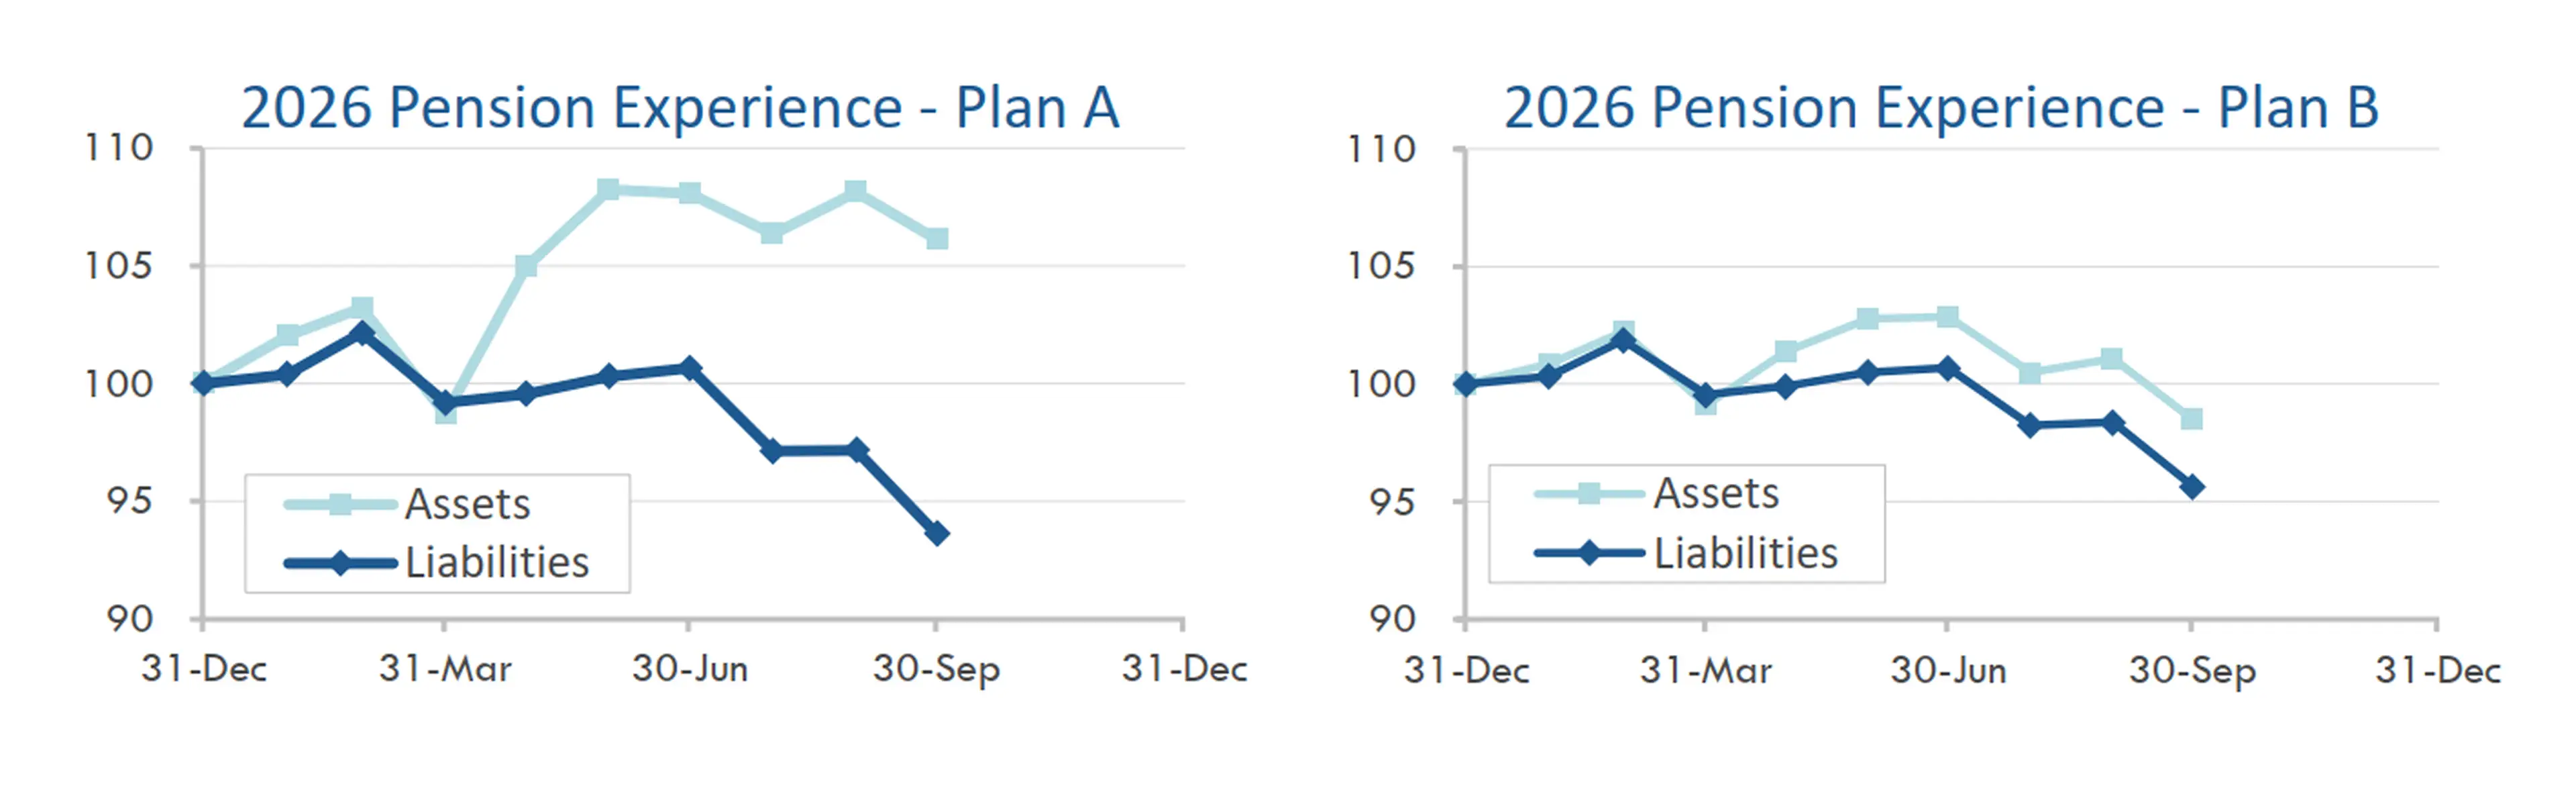
Higher stock prices and higher interest rates mean pension finances remain on track for a very good year in 2026, the eighth consecutive good year going back to 2019. The graphs below show the movement of assets and liabilities during the first three quarters of 2026:
Looking Ahead
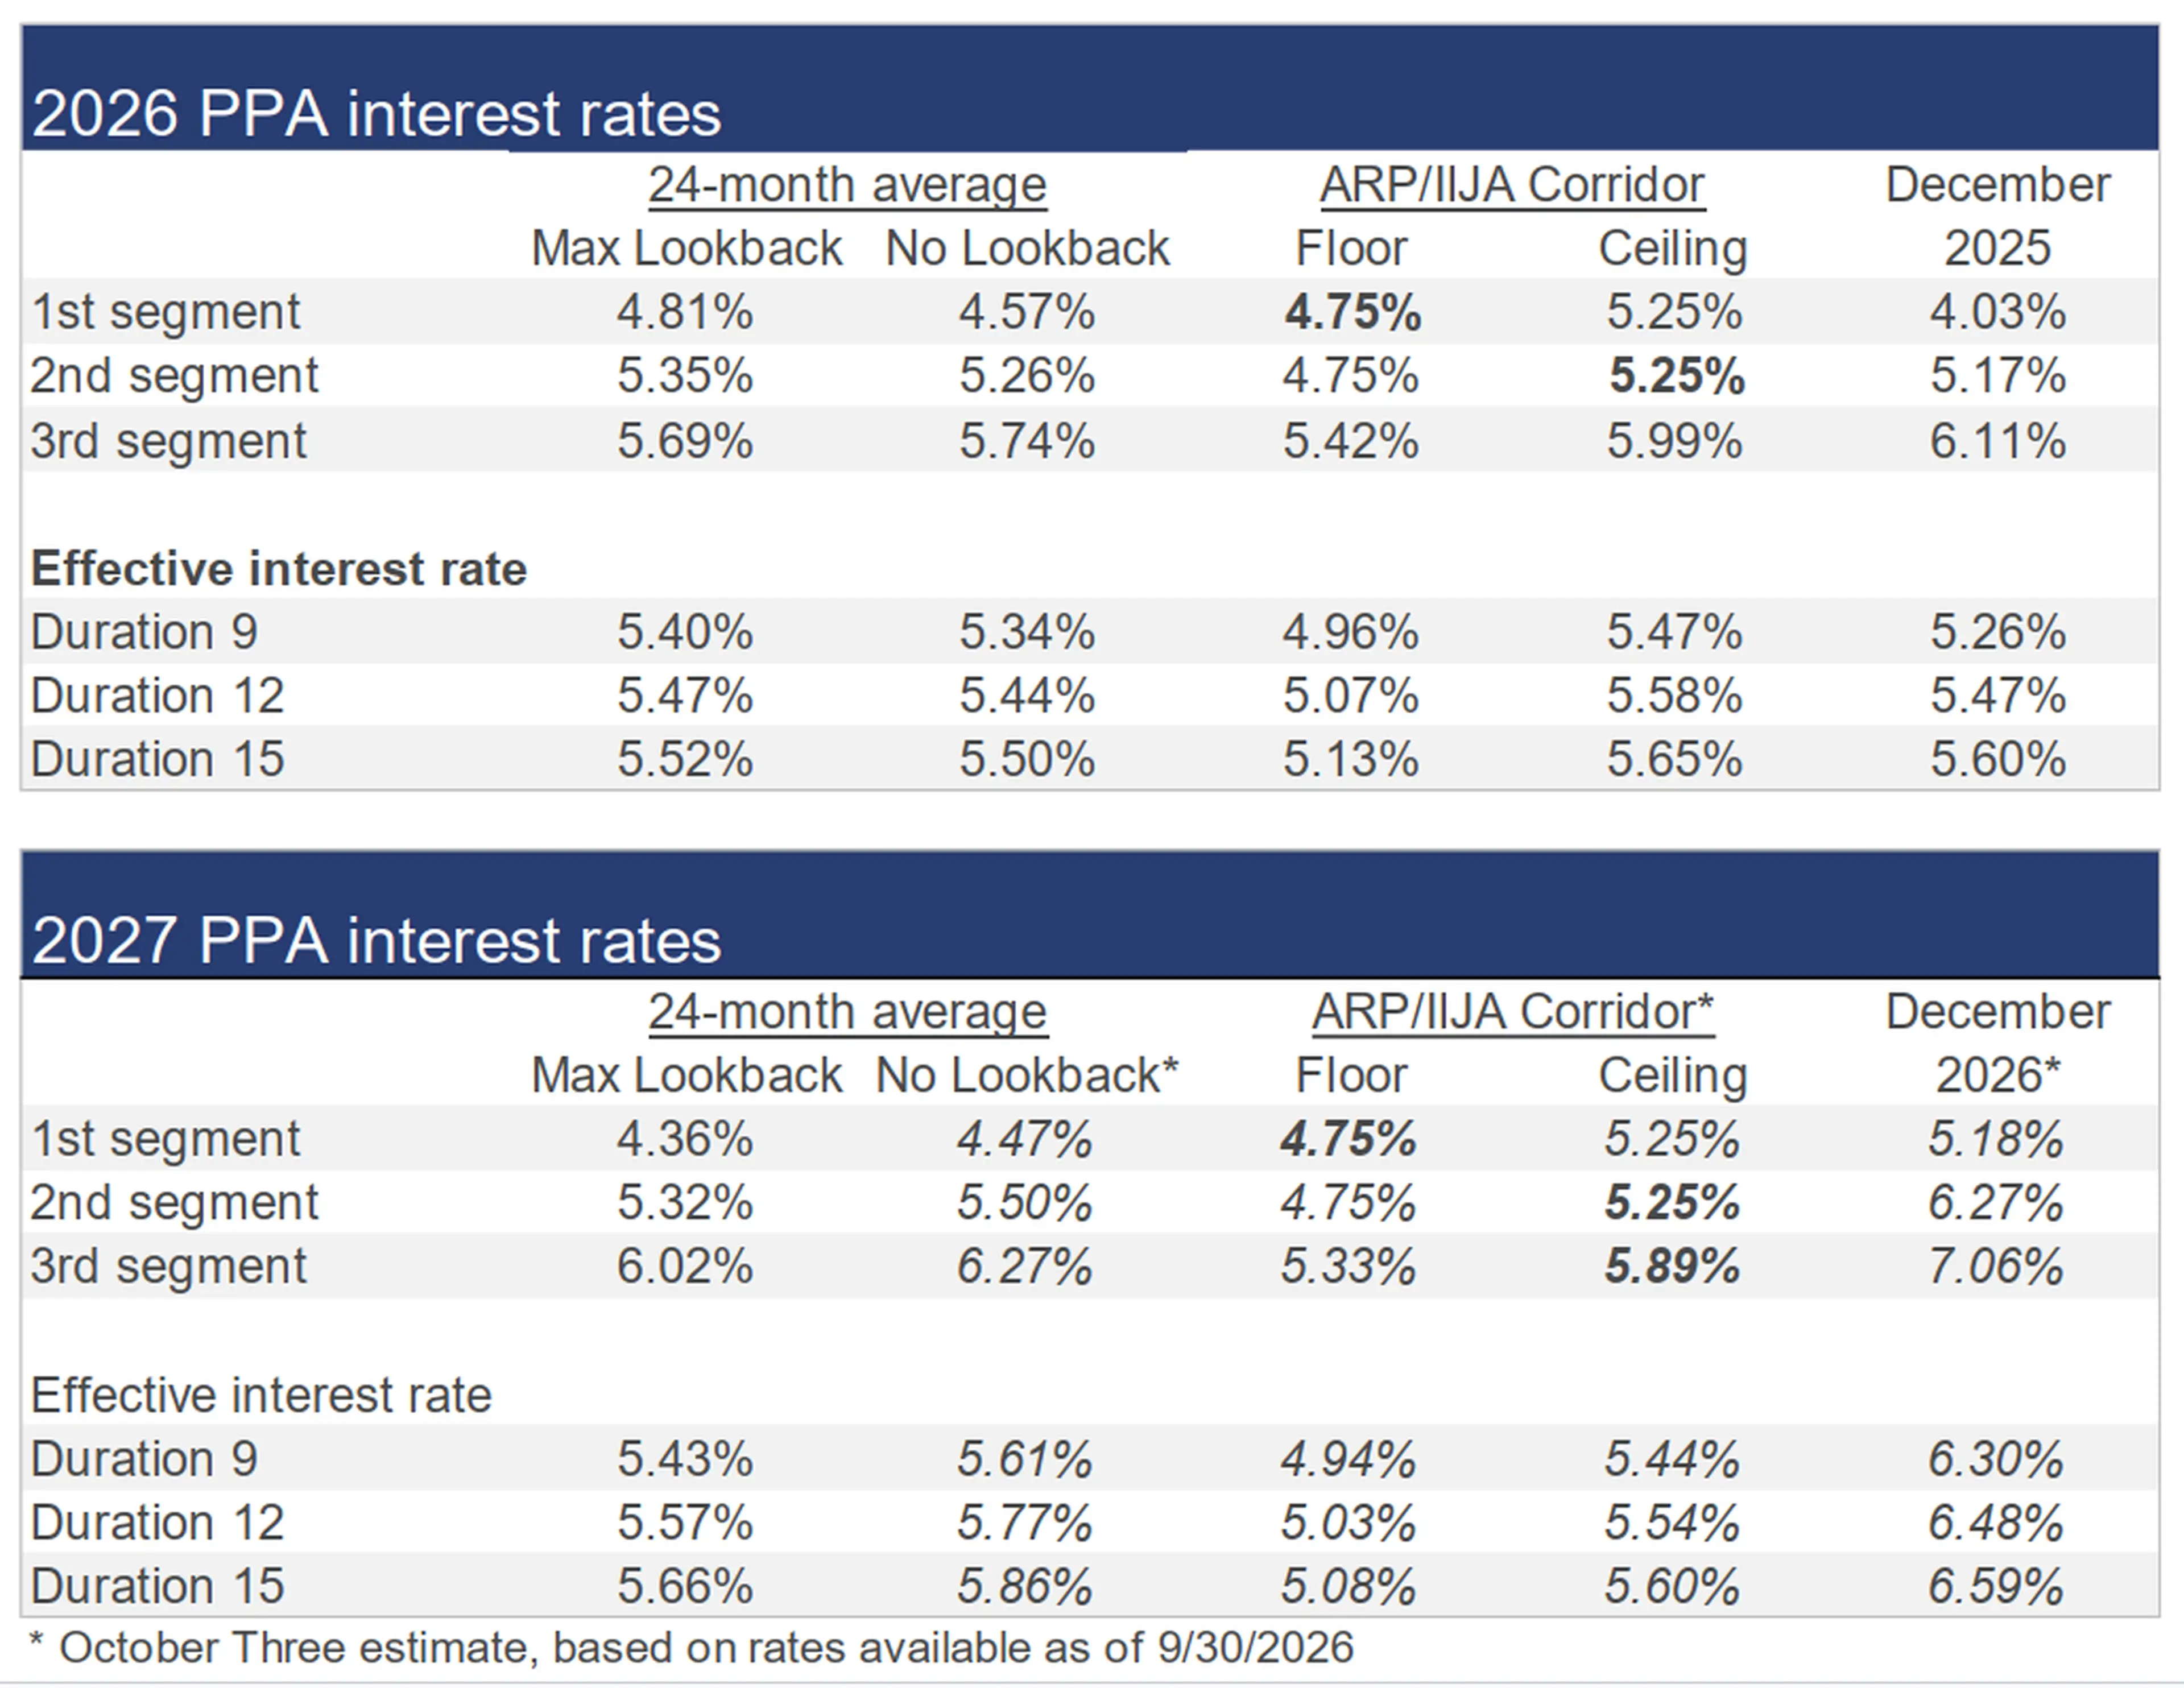
The 30-year US Treasury bond yield at September 30 was 5.64%, the highest yield in more than 24 years. At current rates, pension “funding relief” could force sponsors to overstate liabilities by 10% in 2027 (see table below) and later years, increasing required contributions and forcing some overfunded plans to make additional contributions.
Discount rates increased sharply last month. We expect most pension sponsors will use effective discount rates in the 6.2%-6.6% range to measure liabilities right now. Rates are now the highest they have been since 2009.
The table below summarizes rates that calendar-year plan sponsors are required to use for IRS funding purposes for 2026, along with estimates for 2027, including the rate “corridor” that applies to the 24-month average rates under funding relief for each segment.
1Plan A is a traditional plan (duration 12 at 5.5%) with a 60/40 asset allocation, while Plan B is a largely retired plan (duration 9 at 5.5%) with a 20/80 allocation with a greater emphasis on corporate and long-duration bonds. We assume overhead expenses of 1% of plan assets per year, and we assume the plans are 100% funded at the beginning of the year and ignore benefit accruals, contributions, and benefit payments in order to isolate the financial performance of plan assets versus liabilities.