Loading article...
October 15, 2026
2027 Increases for Retirement Plans, Social Security
The Social Security Administration just announced benefit increases effective in 2027. Current retirees will receive a cost-of-living increase, beginning in January 2027 of 3.6%, reflecting the increase in CPI-W between the 3rd quarter of 2025 and the 3rd quarter of 2026.
In addition, the maximum amount of earnings subject to Social Security tax will increase in 2026 from $184,500 to $192,300, based on a 4.2% increase in the ‘national average wage’ during 2025.
These changes will affect benefits for currently retired individuals, as well as those contemplating retirement. Employers who sponsor retirement plans that are ‘coordinated’ with Social Security in some fashion will also see an impact on benefits earned and payable under such plans.
IRS Limits
IRS will soon release limits applicable to retirement plans for various purposes in 2027, based on a 3.50% increase in CPI-U between the 3rd quarter of 2025 and the 3rd quarter of 2026. Based on this increase, we expect increases in most limits applicable to retirement plans in 2027. The table below summarizes our calculations for 2027, along with values for 2026 and 2025:
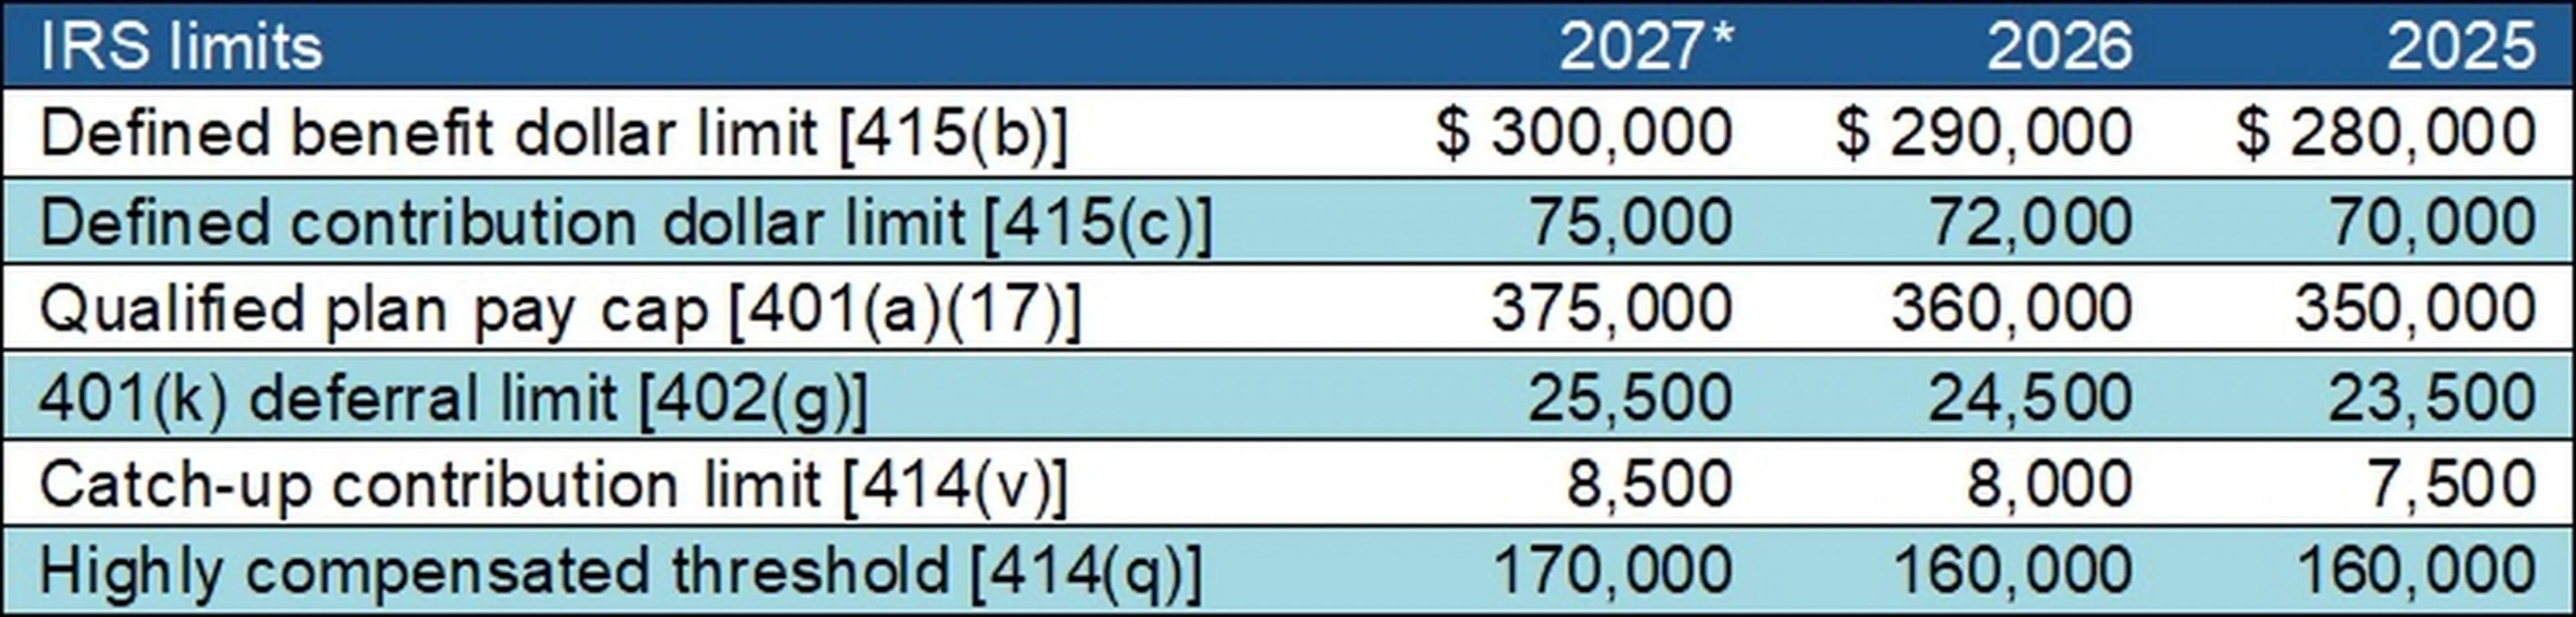
* Based on October Three calculations
PBGC Amounts
The increase in national average wages also drives some key amounts used in calculating PBGC premiums. Relevant amounts for 2027 (along with 2026 and 2025) are summarized below:
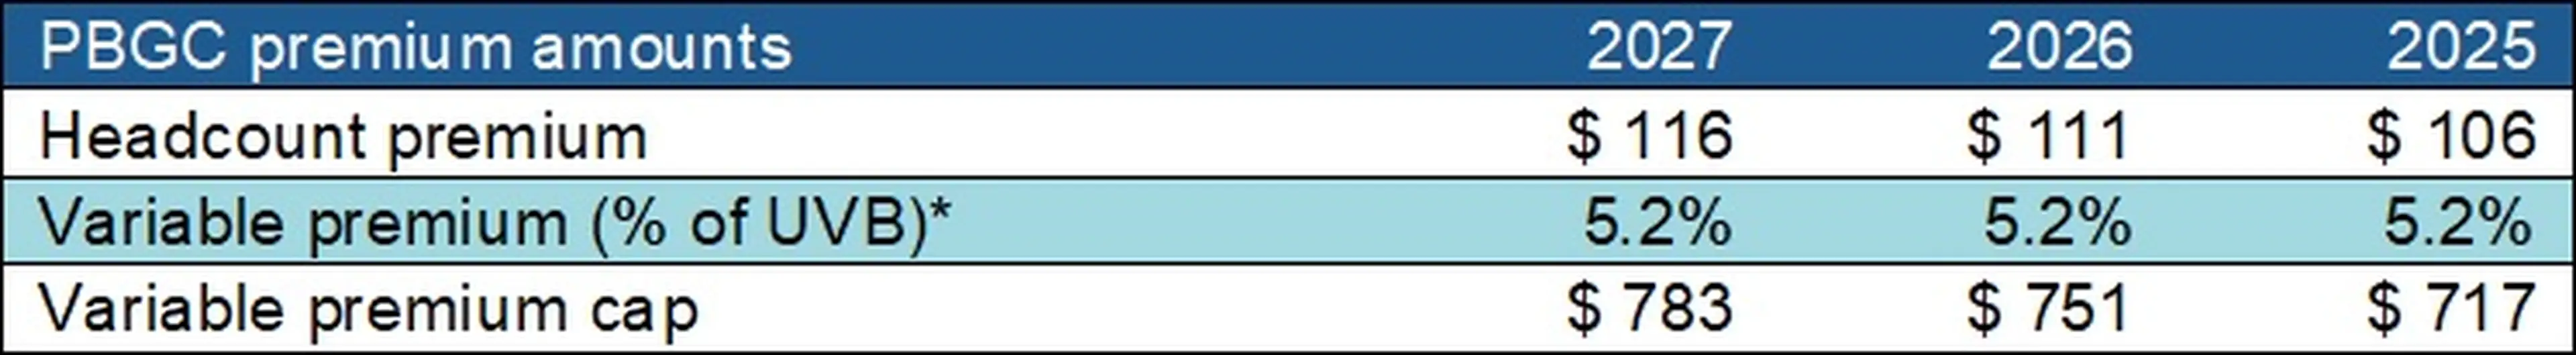
* Capped at 5.2% for 2023 and later
The PBGC headcount premium and variable premium cap are indexed to increases in the national average wage. 2027 amounts reflect a 4.2% increase in the national average wage during 2025.