Loading article...
October 15, 2026
October 2026 Pension Risk Transfer Pricing Update
Executive Summary
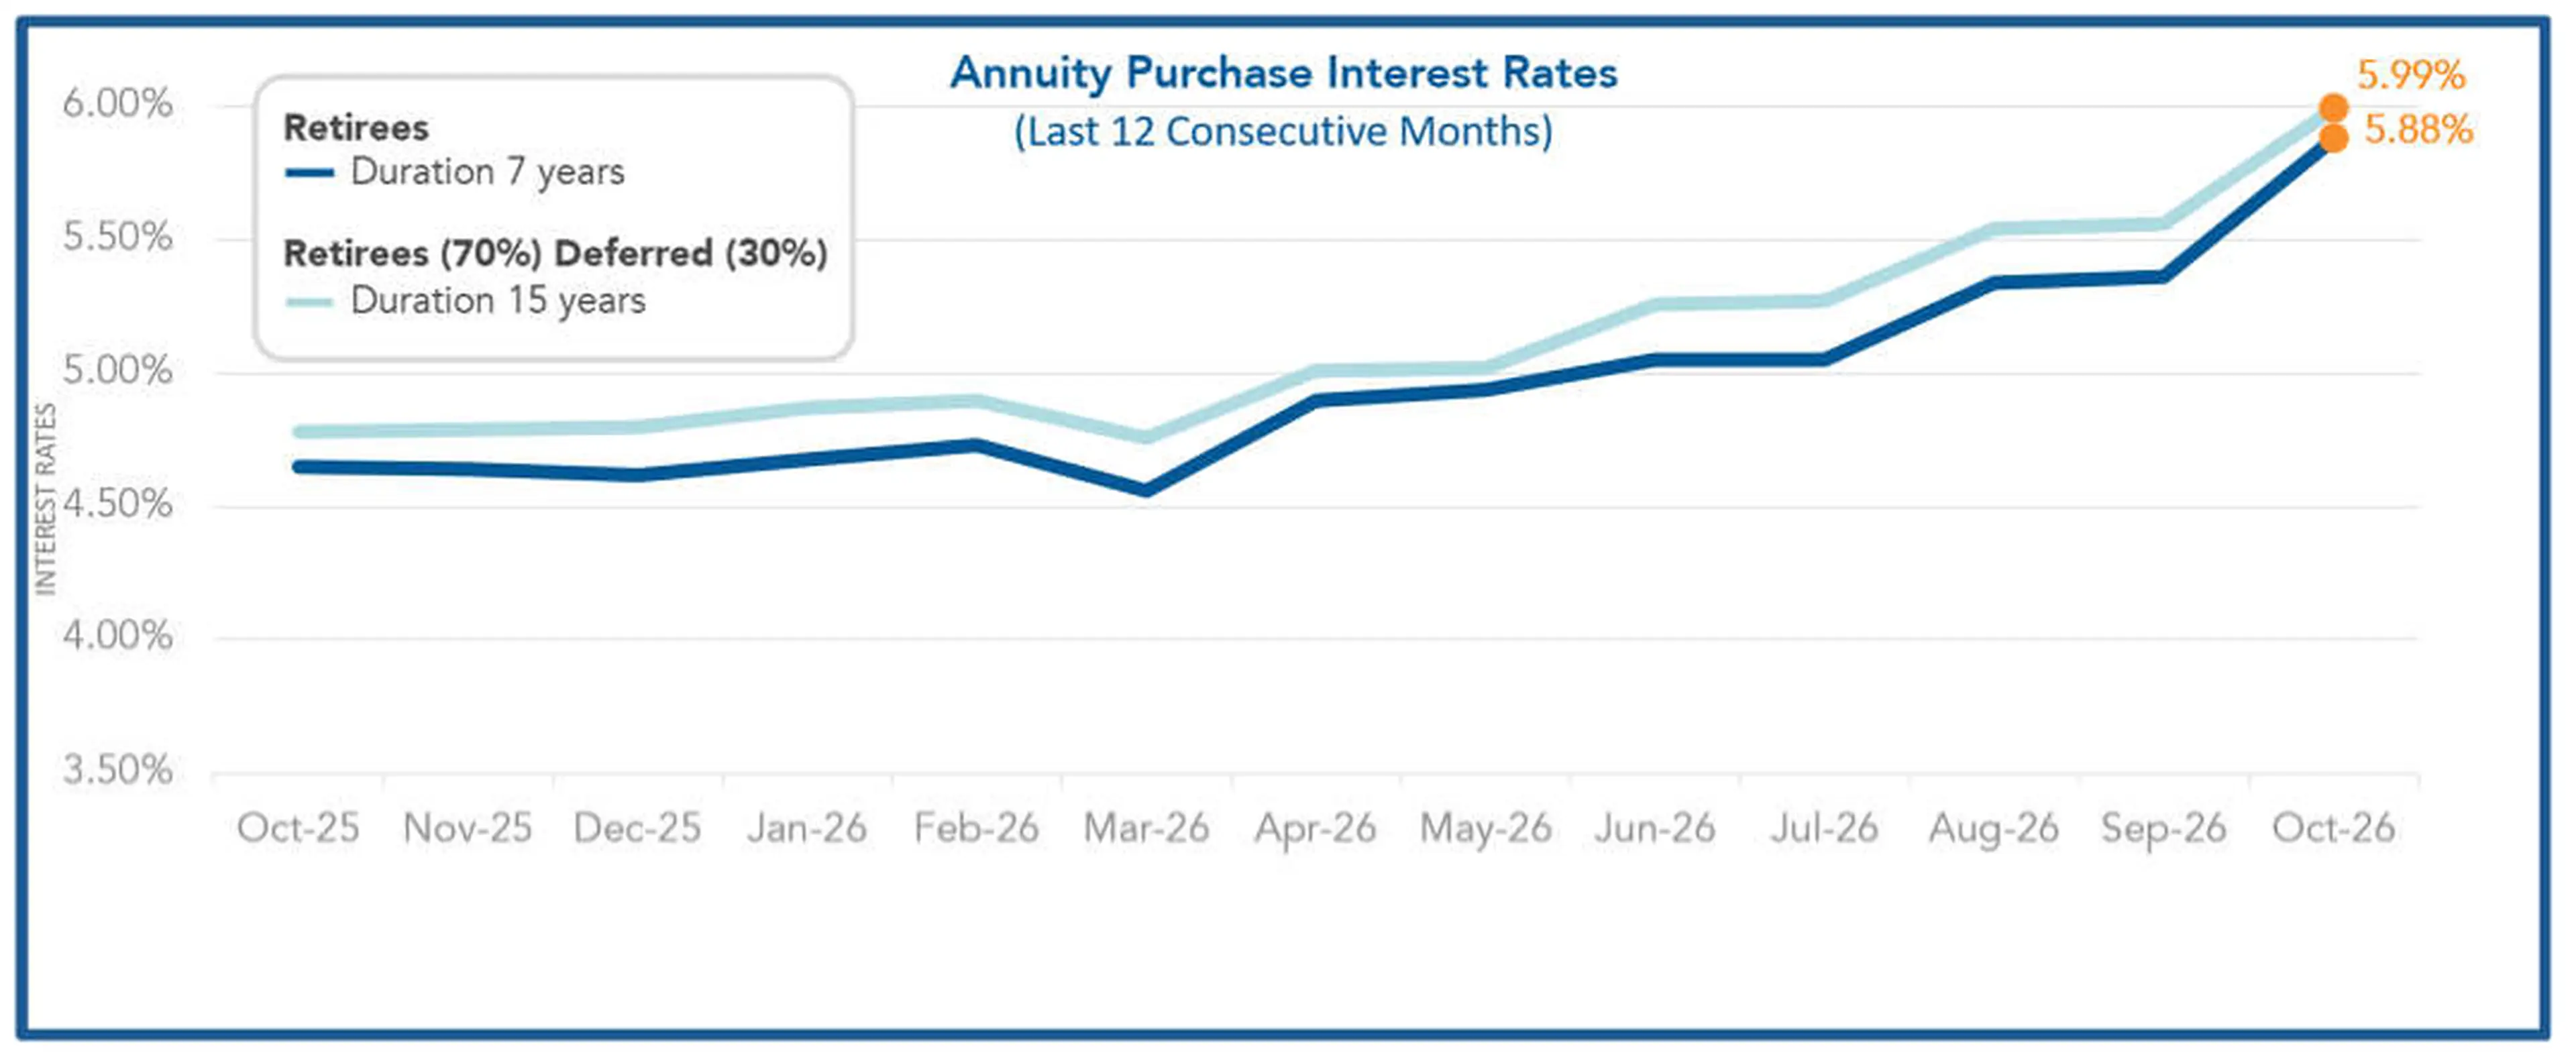
The Pension Risk Transfer marketplace is entering the fourth quarter with continuous momentum, supported by the record-high annuity purchase interest rates. Both the duration 7 and duration 15 rates have reached historic highs at the start of the month. Since January 2026, the duration 7 rate has increased 120 basis points, while the duration 15 rate has climbed 112 basis points. These favorable rate movements are creating attractive opportunities and a comfortable environment for plan sponsors to continue to reduce pension risk.
In the last few years, insurer participation, industry education, and the range of de-risking solutions have continued to expand significantly in the PRT marketplace. Accompanied by favorable market and interest rate conditions, this combination presents a very strong window of opportunity for plan sponsors to begin evaluating strategies for de-risking their plans.
In case you missed it, October Three’s 2026 Pension Risk Transfer Trend Report highlights a changing market in which favorable pension funding conditions coexist with slower transaction activity. Insurers surveyed reported 216 transactions totaling $6.05 billion in premiums during the first half of 2026, with plan terminations accounting for 66% of transactions. Despite opportunities created by interest rates and pension funding levels, most surveyed insurers reported lower transaction volumes and premiums compared with the first half of 2025. The report also emphasizes the importance of accurate participant data in reducing implementation delays and identifies continued competition among insurers as a key market dynamic. For pension plan sponsors, the findings underscore the importance of evaluating market conditions, preparing plan data, and carefully assessing de-risking strategies; read the full 2026 Pension Risk Transfer Trend Report for the complete analysis and insurer outlook.
Pricing Update
Both the duration 7 and duration 15 annuity purchase interest rates are at the highest they’ve been in years reaching 5.88% and 5.99%. These continued upward trends signal encouraging opportunities for plan sponsors evaluating de-risking solutions. Following a slower start to the year, insurers may offer more competitive pricing in the fourth quarter as they work to meet their annual goals. This dynamic can create valuable opportunities for plan sponsors to explore attractive prices and secure favorable annuity purchase rates. However, the year is coming to a close and taking advantage of these conditions requires advanced planning. Given the current rate trends in the marketplace, plan sponsors should highly consider connecting with annuity search firms. Beginning the process early can provide plan sponsors with a larger window to navigate their options and enter the marketplace timely to capitalize on these favorable conditions.
Historical Activity
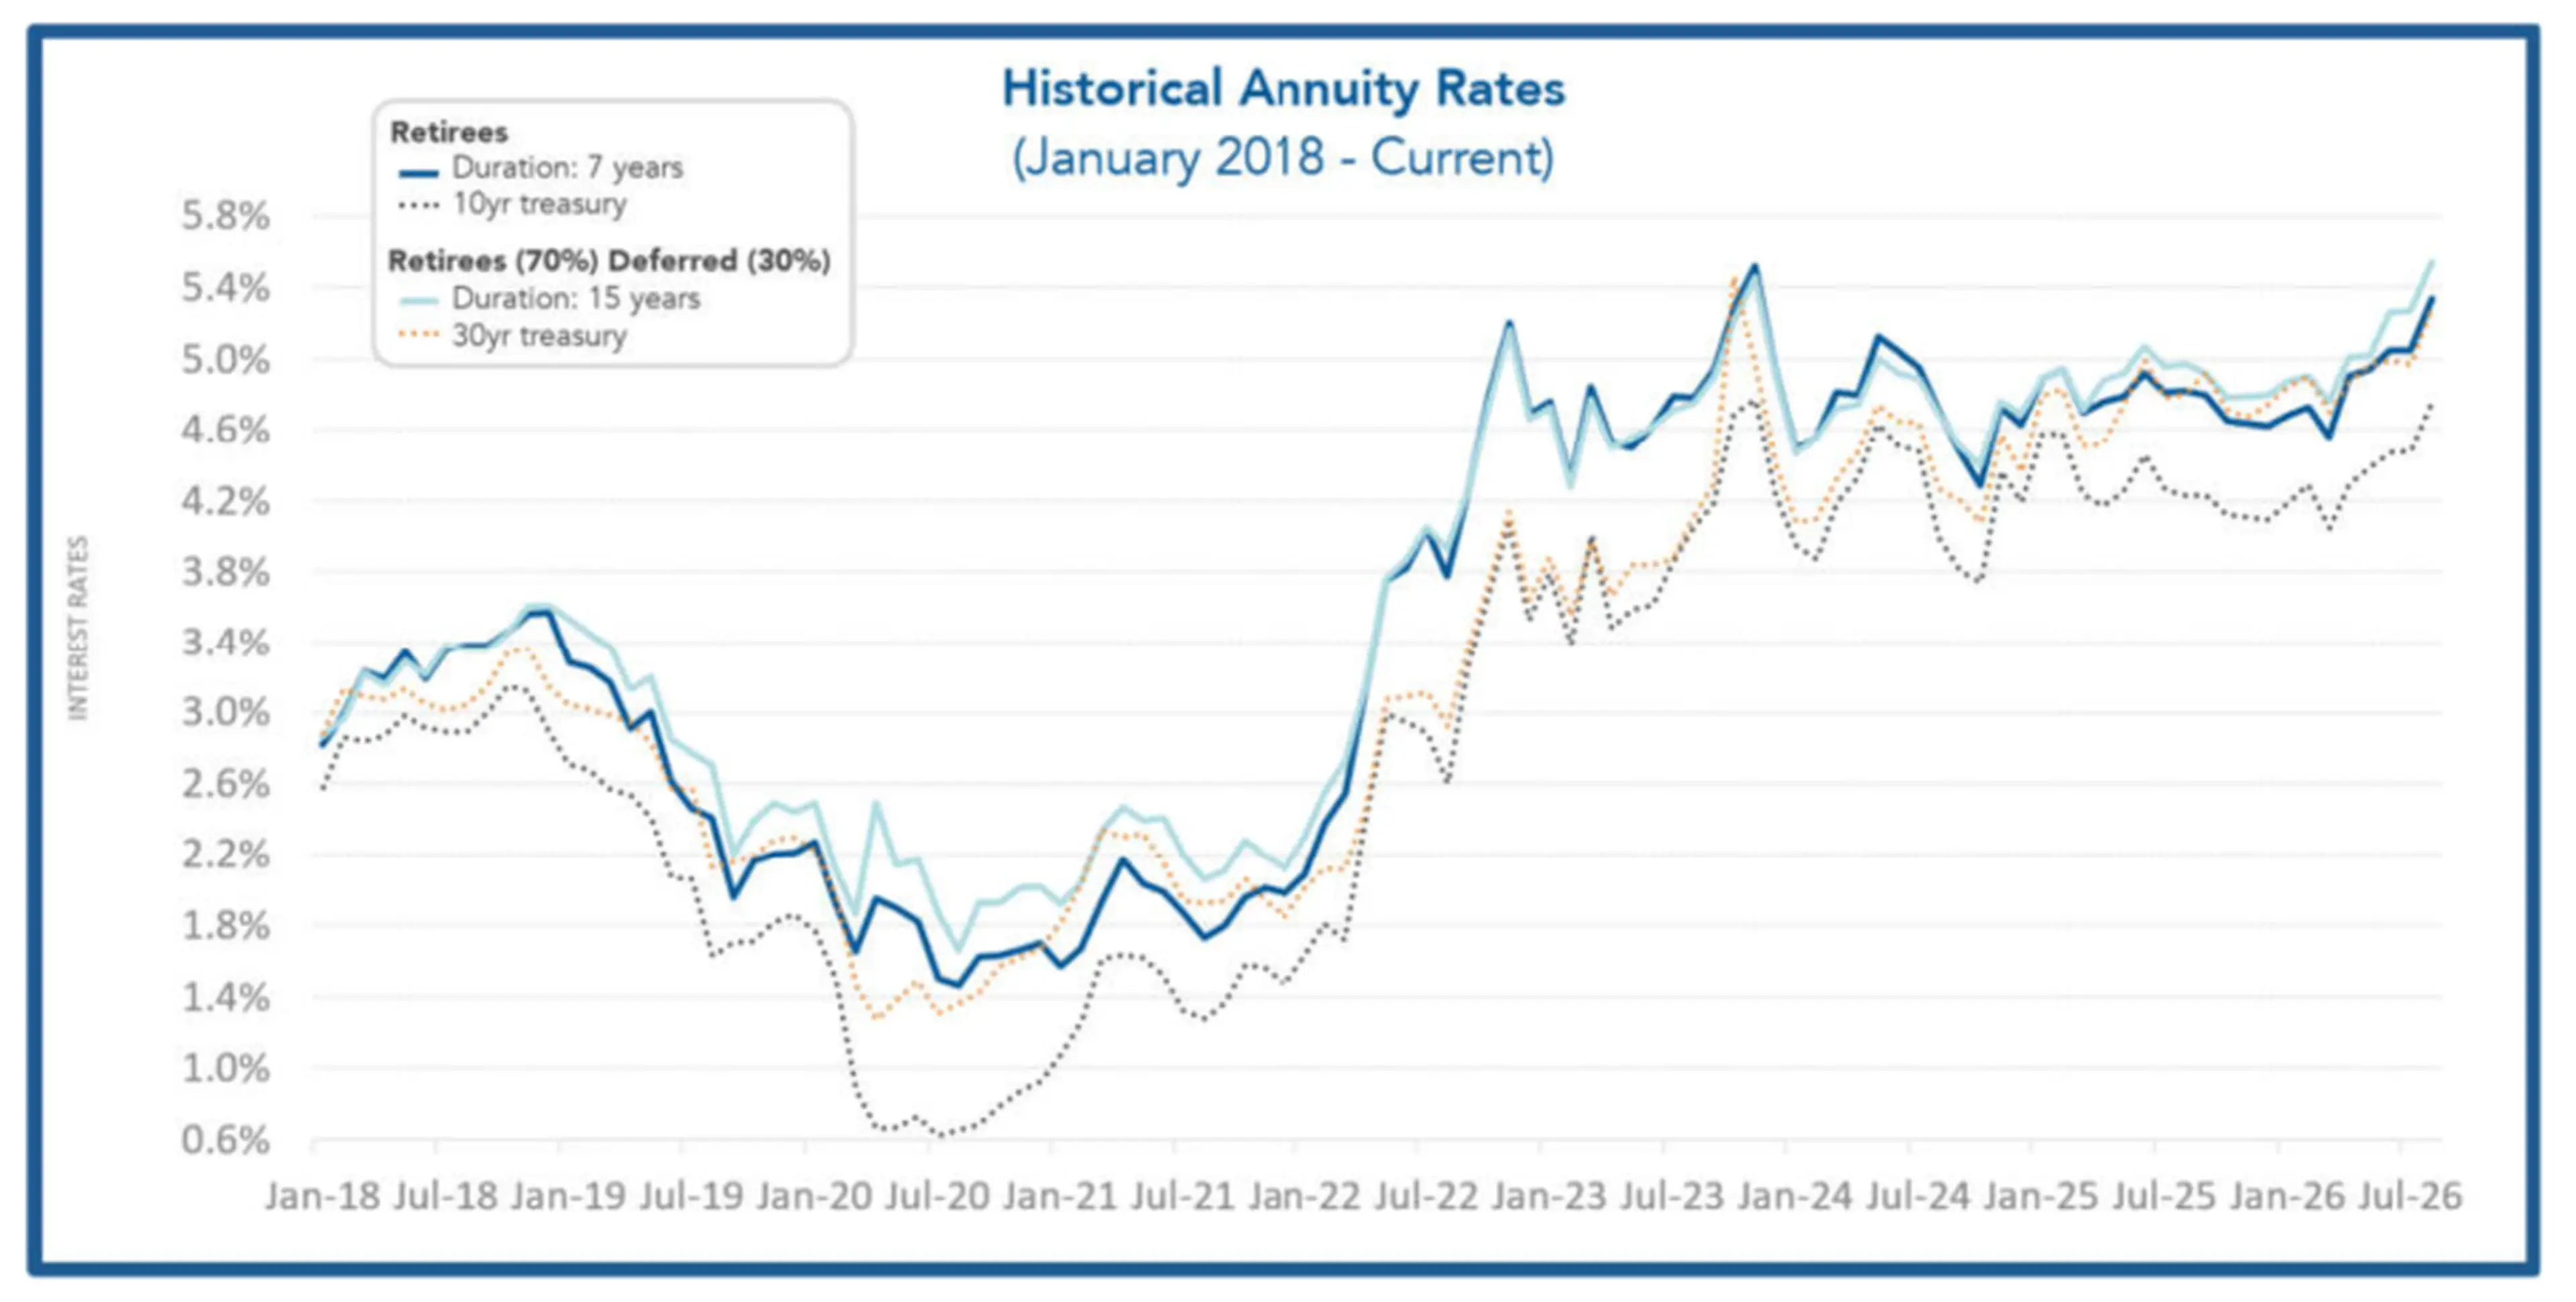
Both the 10-year and 30-year Treasury rates increased significantly in October, reaching 5.24% and 5.61%. For plan sponsors evaluating PRT opportunities, the broader interest rate environment is an important consideration. Treasury rates can influence corporate bonds, which play a key role in annuity pricing. Insurers rely on corporate bonds to value pension obligations and determine the pricing of transactions. Consequently, any movement in corporate bonds can affect the cost of transferring pension liabilities to insurers. As highlighted in the Pension Finance Update, the combination of rising stock prices and elevated interest rates has pension finances are on track for another strong year in 2026. If these trends hold, 2026 would mark the eighth consecutive year of favorable pension performance, extending a positive trend that began in 2019. Persistently elevated interest rates can help reduce pension liabilities and improve funded status for many pension plans.
Annuity Costs Relative to GAAP
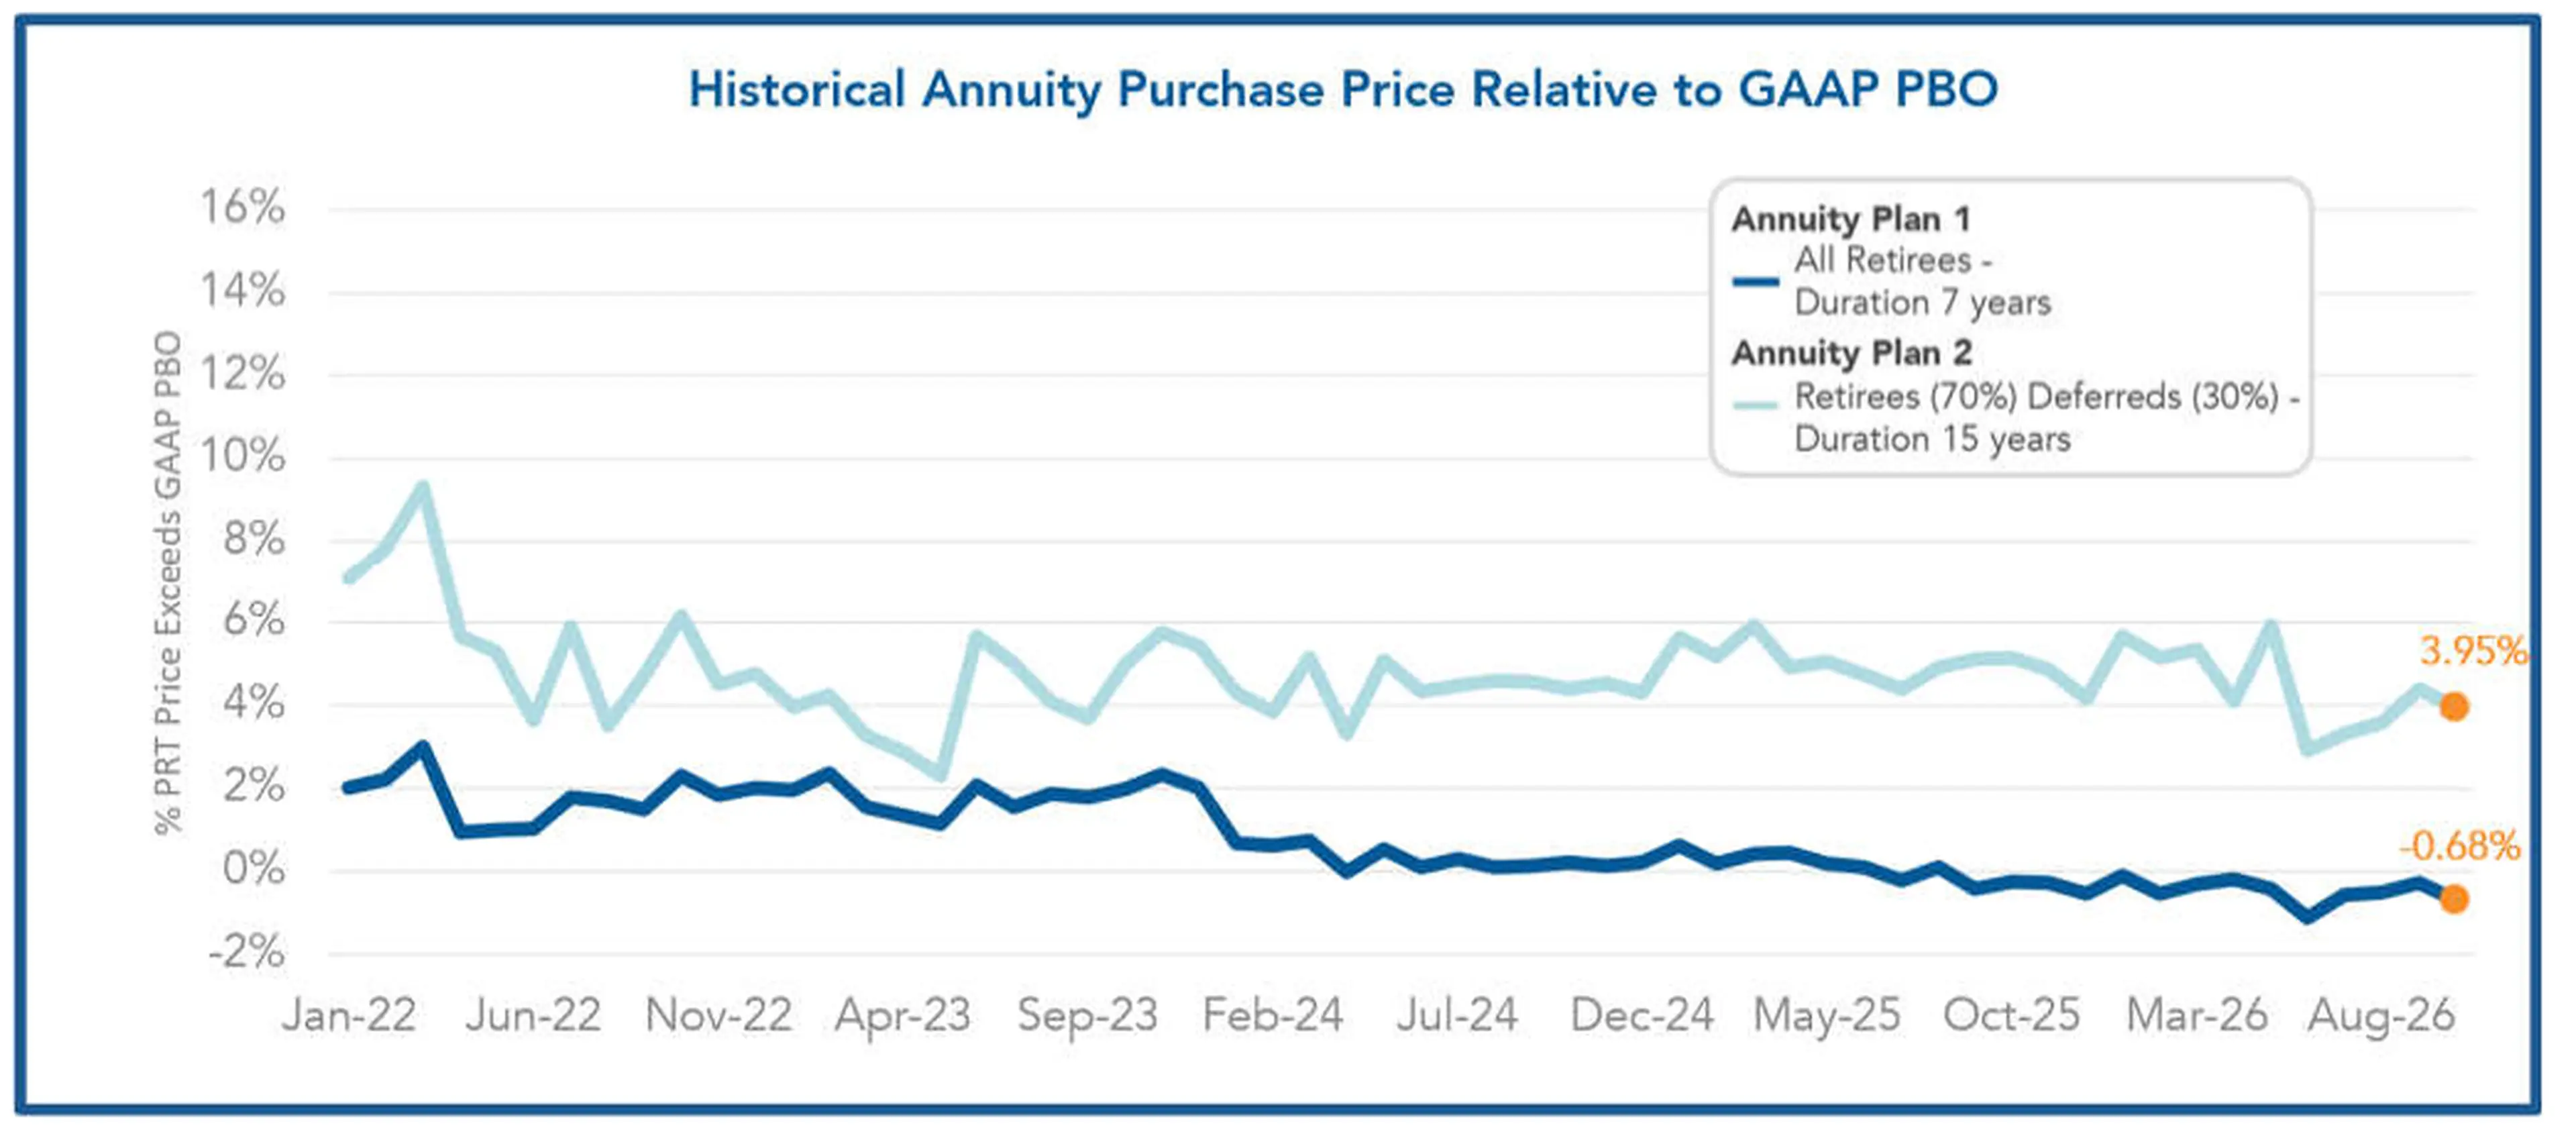
The graph below shows the spread between the annuity purchase price and the GAAP projected benefit obligation (PBO), also referred to as the accounting book value. This month, we observed Annuity Plan 1 spread at approximately -0.68% while Annuity Plan 2’s sits at 3.95%. As annuity purchase rates increase, purchase prices drop relative to the PBO. Please note that the PBO figures shown do not include future overhead costs—such as administrative expenses and PBGC premiums—that plan sponsors would incur by retaining participants in the plan.
2026 PRT Trends Report
Pension risk transfer (PRT) remains an important consideration for organizations looking to reduce the financial and administrative risks associated with defined benefit pension plans. However, the latest market data reveals a more nuanced picture: while pension funding levels and annuity pricing conditions continue to create opportunities for plan sponsors, transaction activity has slowed.
According to October Three’s 2026 Pension Risk Transfer Trend Report, surveyed insurers reported 216 transactions totaling $6.05 billion in premiums during the first half of 2026. Plan terminations accounted for 66% of reported transactions, making them the dominant transaction type. Nevertheless, 94% of surveyed carriers reported a decline in transaction volume compared with the first half of 2025.
The report also highlights the importance of preparation. Incomplete participant data remains a significant obstacle to efficient implementation, contributing to longer onboarding timelines and additional expenses. Meanwhile, insurers anticipate continued competition in the PRT market, even as they forecast lower full-year transaction volumes than in 2025.
For pension plan sponsors, the findings underscore the importance of evaluating funding levels, understanding annuity pricing, preparing accurate plan data, and carefully assessing the costs and benefits of a potential risk transfer. Favorable market conditions may create opportunities, but the right strategy depends on each plan’s financial position and objectives.
For a deeper look at pension funding trends, annuity pricing, transaction activity, insurer expectations, and the factors shaping the market, check out October Three’s 2026 Pension Risk Transfer Trend Report
For additional information or inquiries about the pension risk transfer marketplace, contact Mark Unhoch: munhoch@octoberthree.com.
Submission box. If you want to see some topics covered, submit here
*October Three advises plan sponsors through every step of the Pension Risk Transfer (PRT) process. Through long established relationships with insurers in the PRT marketplace, October Three collects annuity purchase rates for Duration 7 years and Duration 15 years on a monthly basis. We have constructed 2 hypothetical annuity plans which have been valued using the latest mortality tables and mortality improvement scales. Annuity Plan 1 contains retirees only and has a liability duration of 7 years. Annuity Plan 2 contains 70% retirees and 30% deferreds and has a liability duration of 15 years. Monthly annuity rates are determined by taking the average Duration 7 and Duration 15 interest rates provided from the insurers. Annuity Plan 1 was valued using the average of the Duration 7-year interest rates collected from insurers and Annuity Plan 2 was valued using the average of the Duration 15-year interest rates collected from insurers. Using the collected annuity purchase rates and 2 hypothetical annuity plans, we have produced the following graphs representative of actual PRT market activity and the corresponding impact on pension plans.