Loading article...
November 16, 2026
November 2026 Pension Risk Transfer Pricing Update
Executive Summary
As 2026 draws to a close, the annuity purchase marketplace has maintained generally positive momentum, despite some recent softening. According to LIMRA’s October publications, U.S. PRT buyout and buy-in sales totaled approximately $3 billion in the third quarter, a 26% decrease compared to the same period in 2025. Despite the decline, nine annuity carriers reported more than $100 million in buyout and buy-in sales during the quarter.
Currently, more than 20 insurers are actively participating in the Pension Risk Transfer marketplace, offering annuity contracts designed to secure participant’s future retirement benefits. Competition among carriers remains strong, supported by increased education and growing confidence in the transaction process, which creates opportunities for plan sponsors to have optimal pricing and high-quality service.
Following the recent midterm elections, the outlook for pension risk transfer remains favorable, with plan sponsors in an equally strong, if not slightly better, position to pursue their de-risking objectives. With 2026 proving to be an excellent year for pension plan terminations, 2027 is shaping up to offer similar opportunities. Elevated interest rates and continued insurer interest provide an attractive environment for sponsors looking to reduce pension liabilities, improve balance sheet certainty, and eliminate ongoing plan risks. While a traditional plan termination typically takes 12 to 18 months, select firms can complete the process in as little as six months. For sponsors considering termination in 2027, beginning the planning process now can provide a meaningful advantage.
Pricing Update
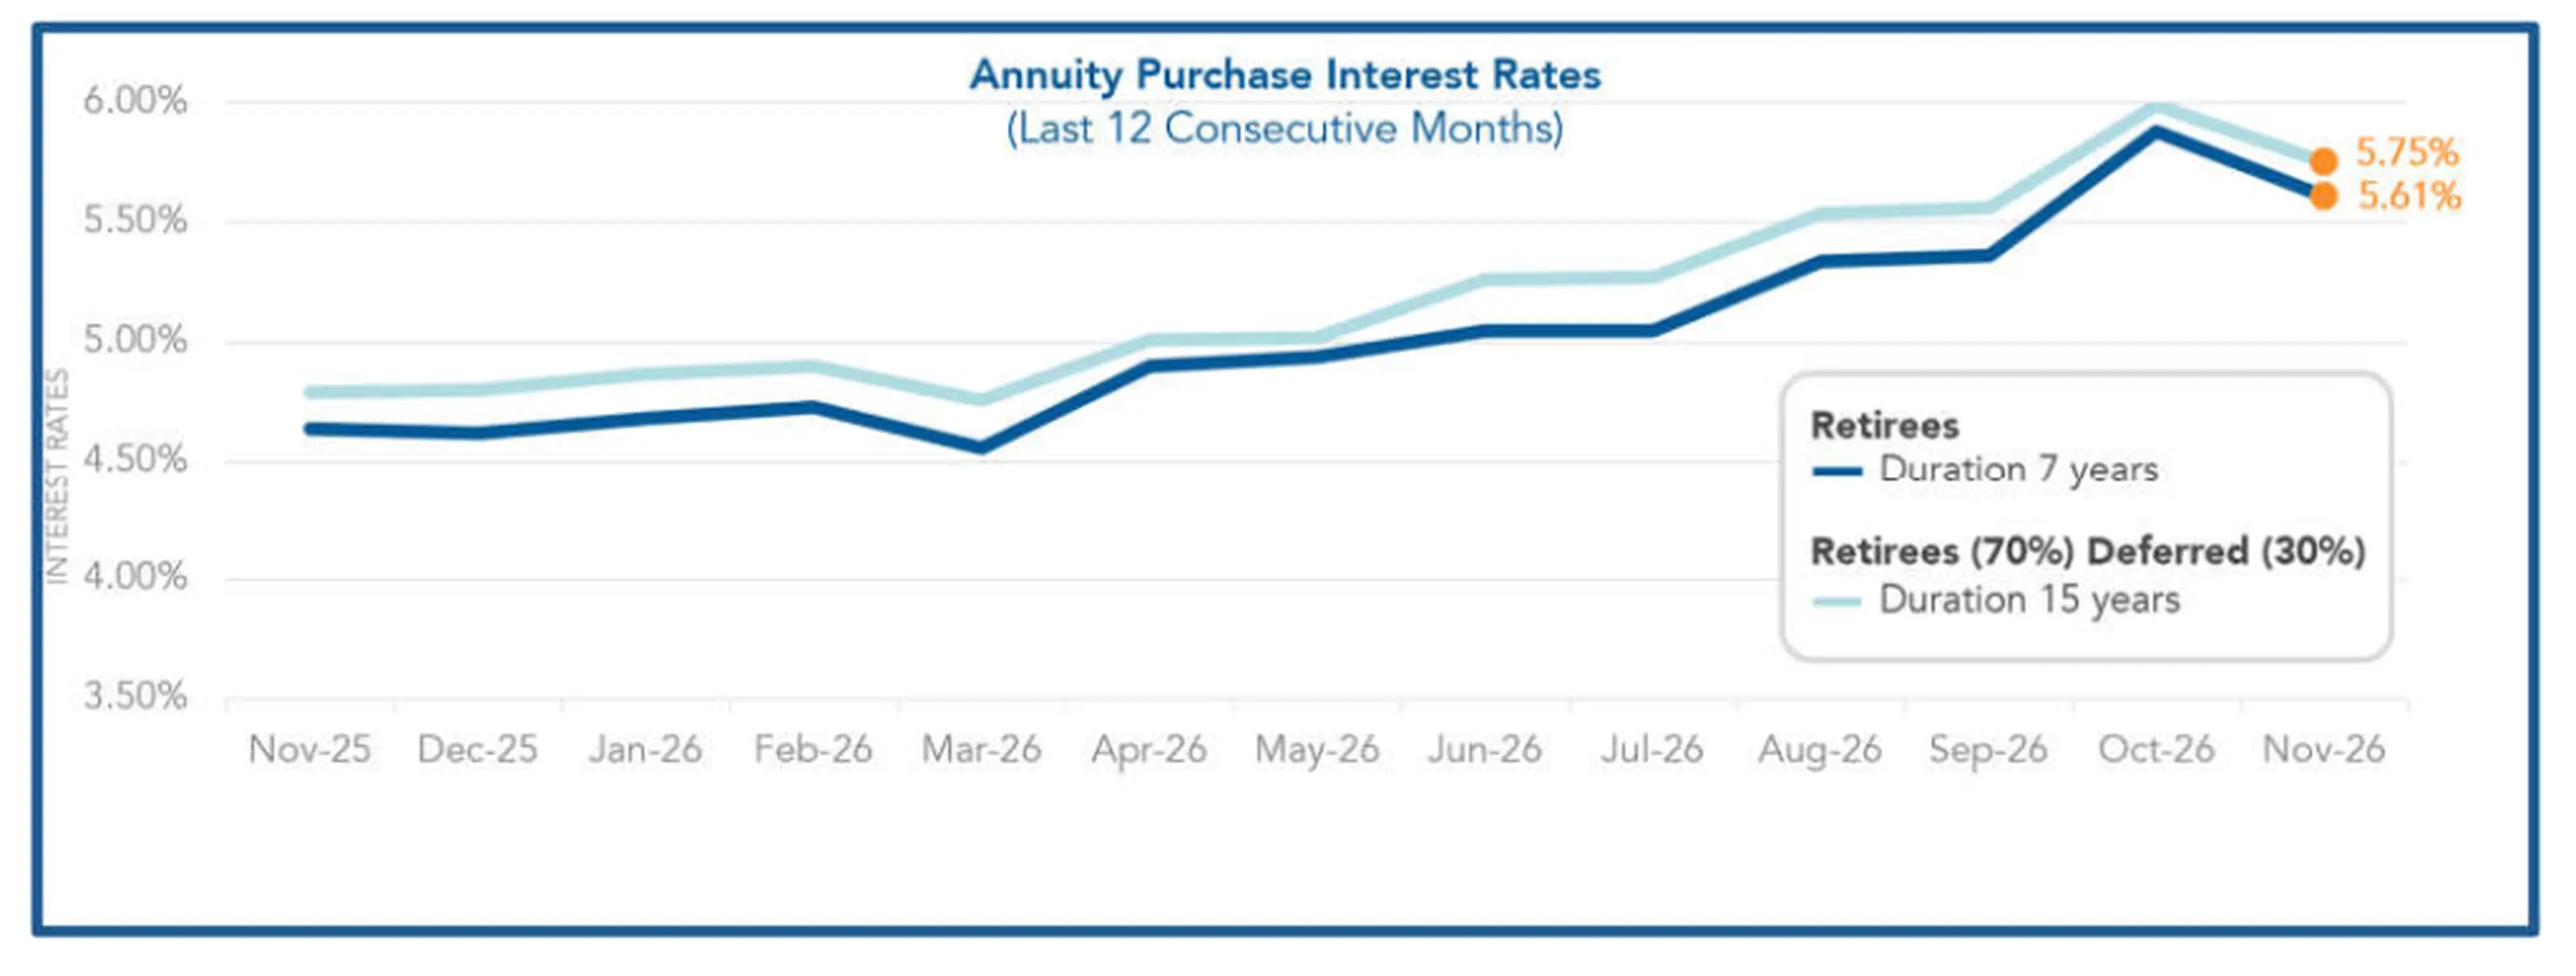
Both the duration 7 and duration 15 annuity purchase interest rates maintained their positive momentum until November where they declined to 5.61% and 5.75%, respectively. Despite these recent decreases, both rates have remained above their respective 2026 averages. Looking ahead into 2027, uncertainty is a constant factor for the direction of annuity purchase interest rates and overall market conditions. Given this uncertainty, plan sponsors should remain proactive in engaging with annuity search firms to remain well-positioned to capitalize on any positive change in market conditions and pursue attractive de-risking opportunities when they arise.
Historical Activity
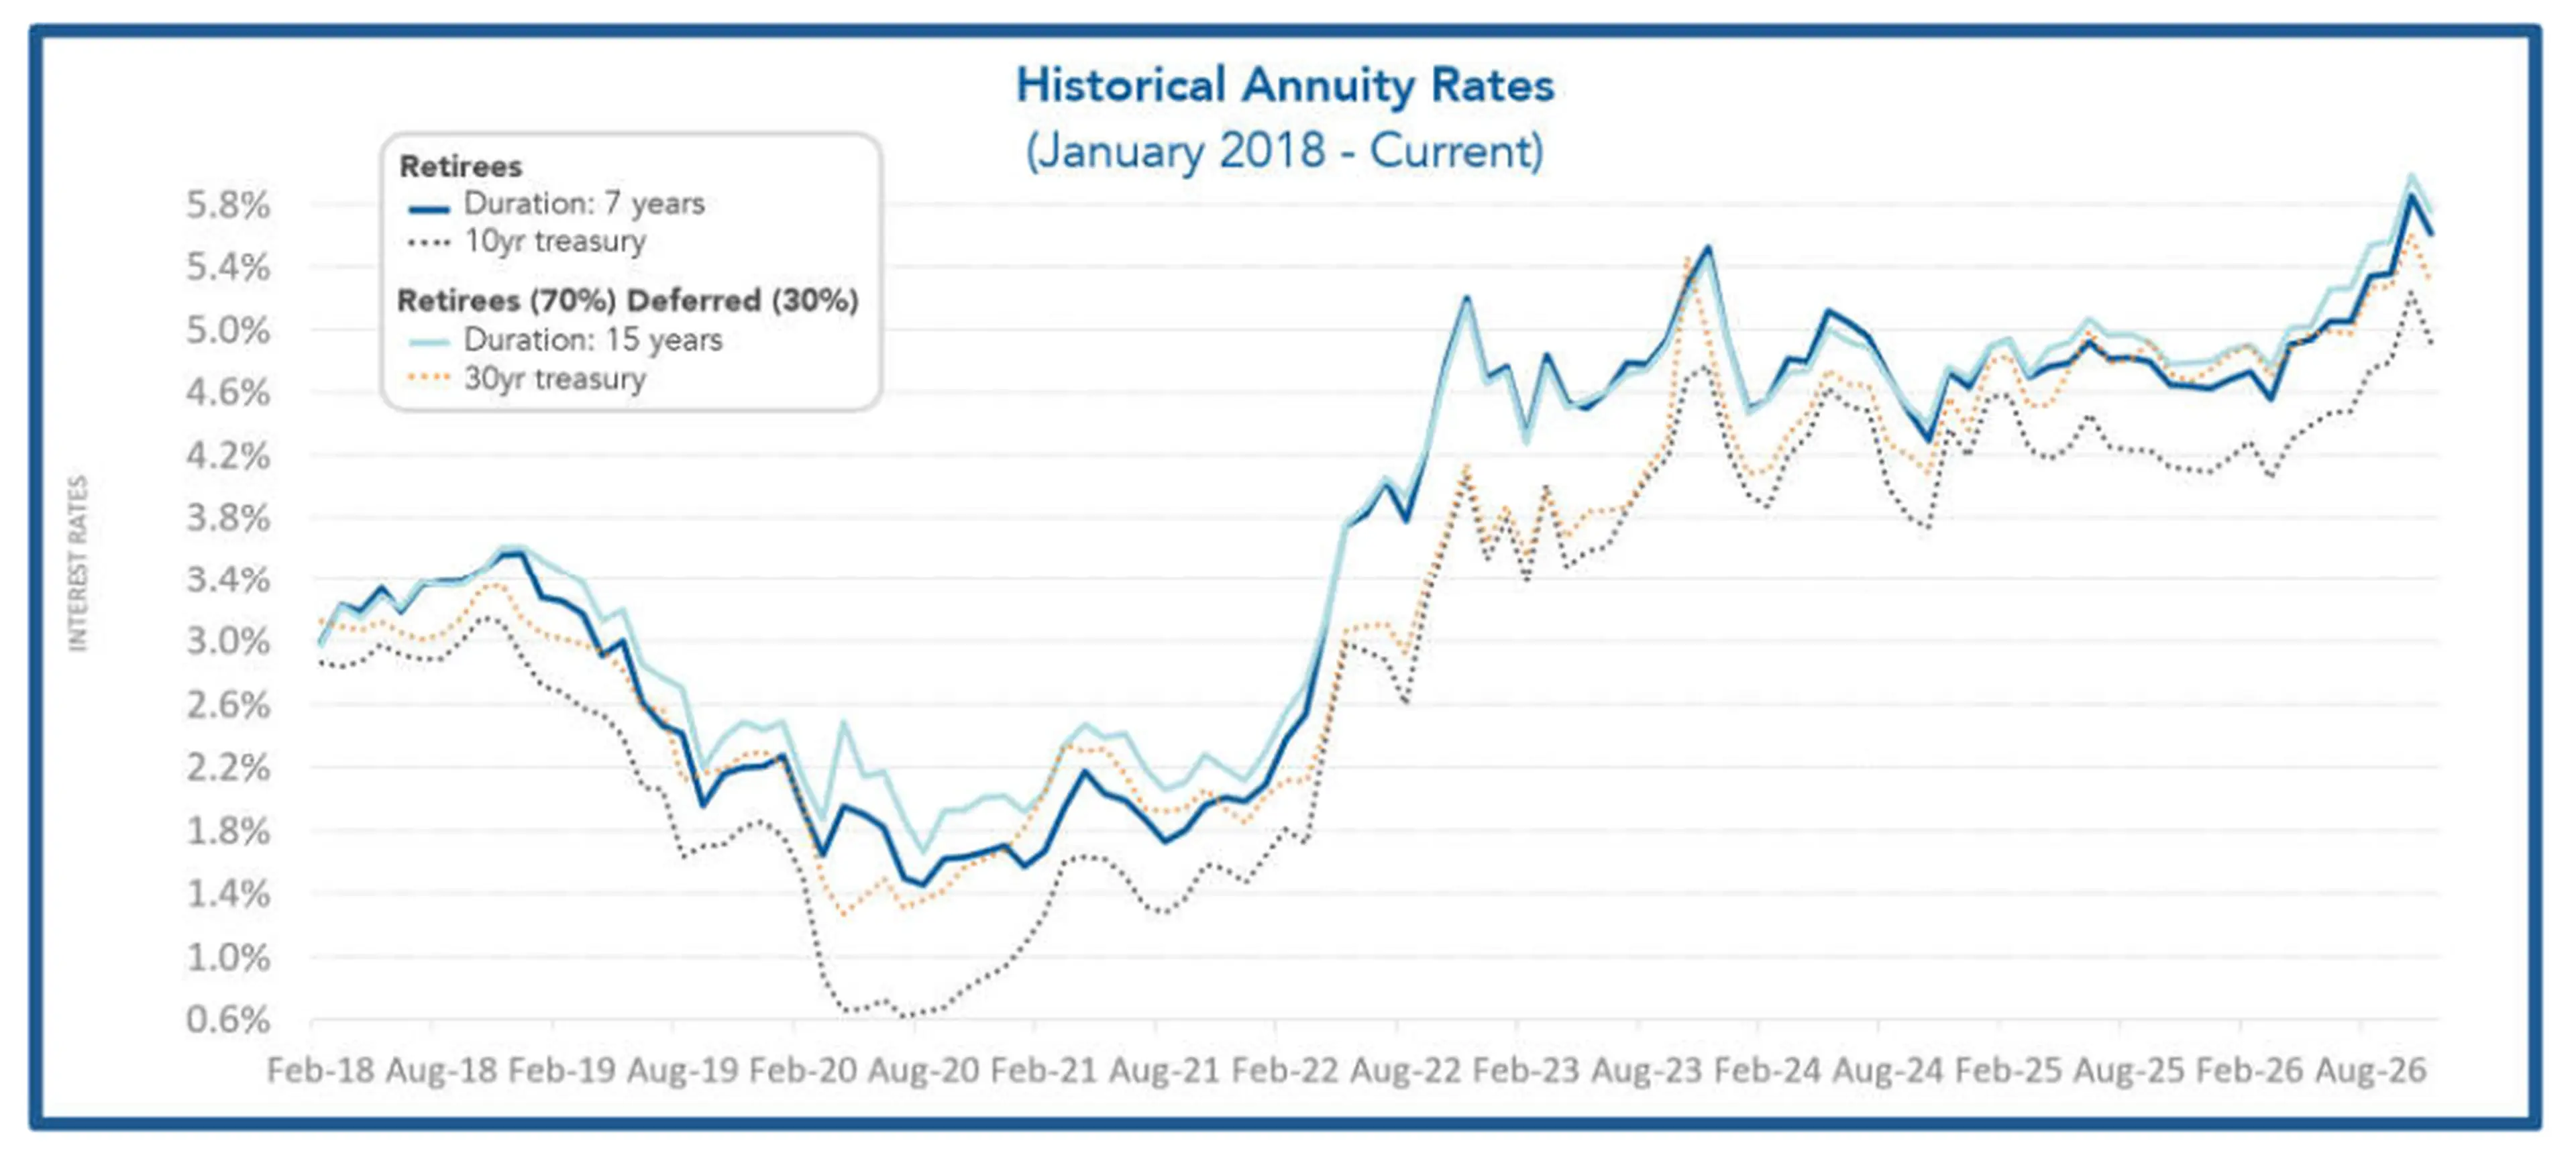
As mentioned in the recent Pension Finance Update declines in stock prices and interest rates created a challenging month in October for pension finances. However, as we continue through the last two months of the year, 2026 is still shaping up to be another impactful one for pension plan sponsors. The 10-year Treasury rate shifted to 4.91% while the 30-year Treasury rate moved to 5.28%. These rates are closely aligned with the annuity purchase interest rates, the 10-year treasury correlating with the duration 7 rate, and the 30-year treasury corresponding with the duration 15 rate. Stability in long-duration yield has historically helped minimize any major increase in plan liabilities, creating more favorable conditions for plan sponsors when exploring pension risk transfer transactions.
Annuity Costs Relative to GAAP
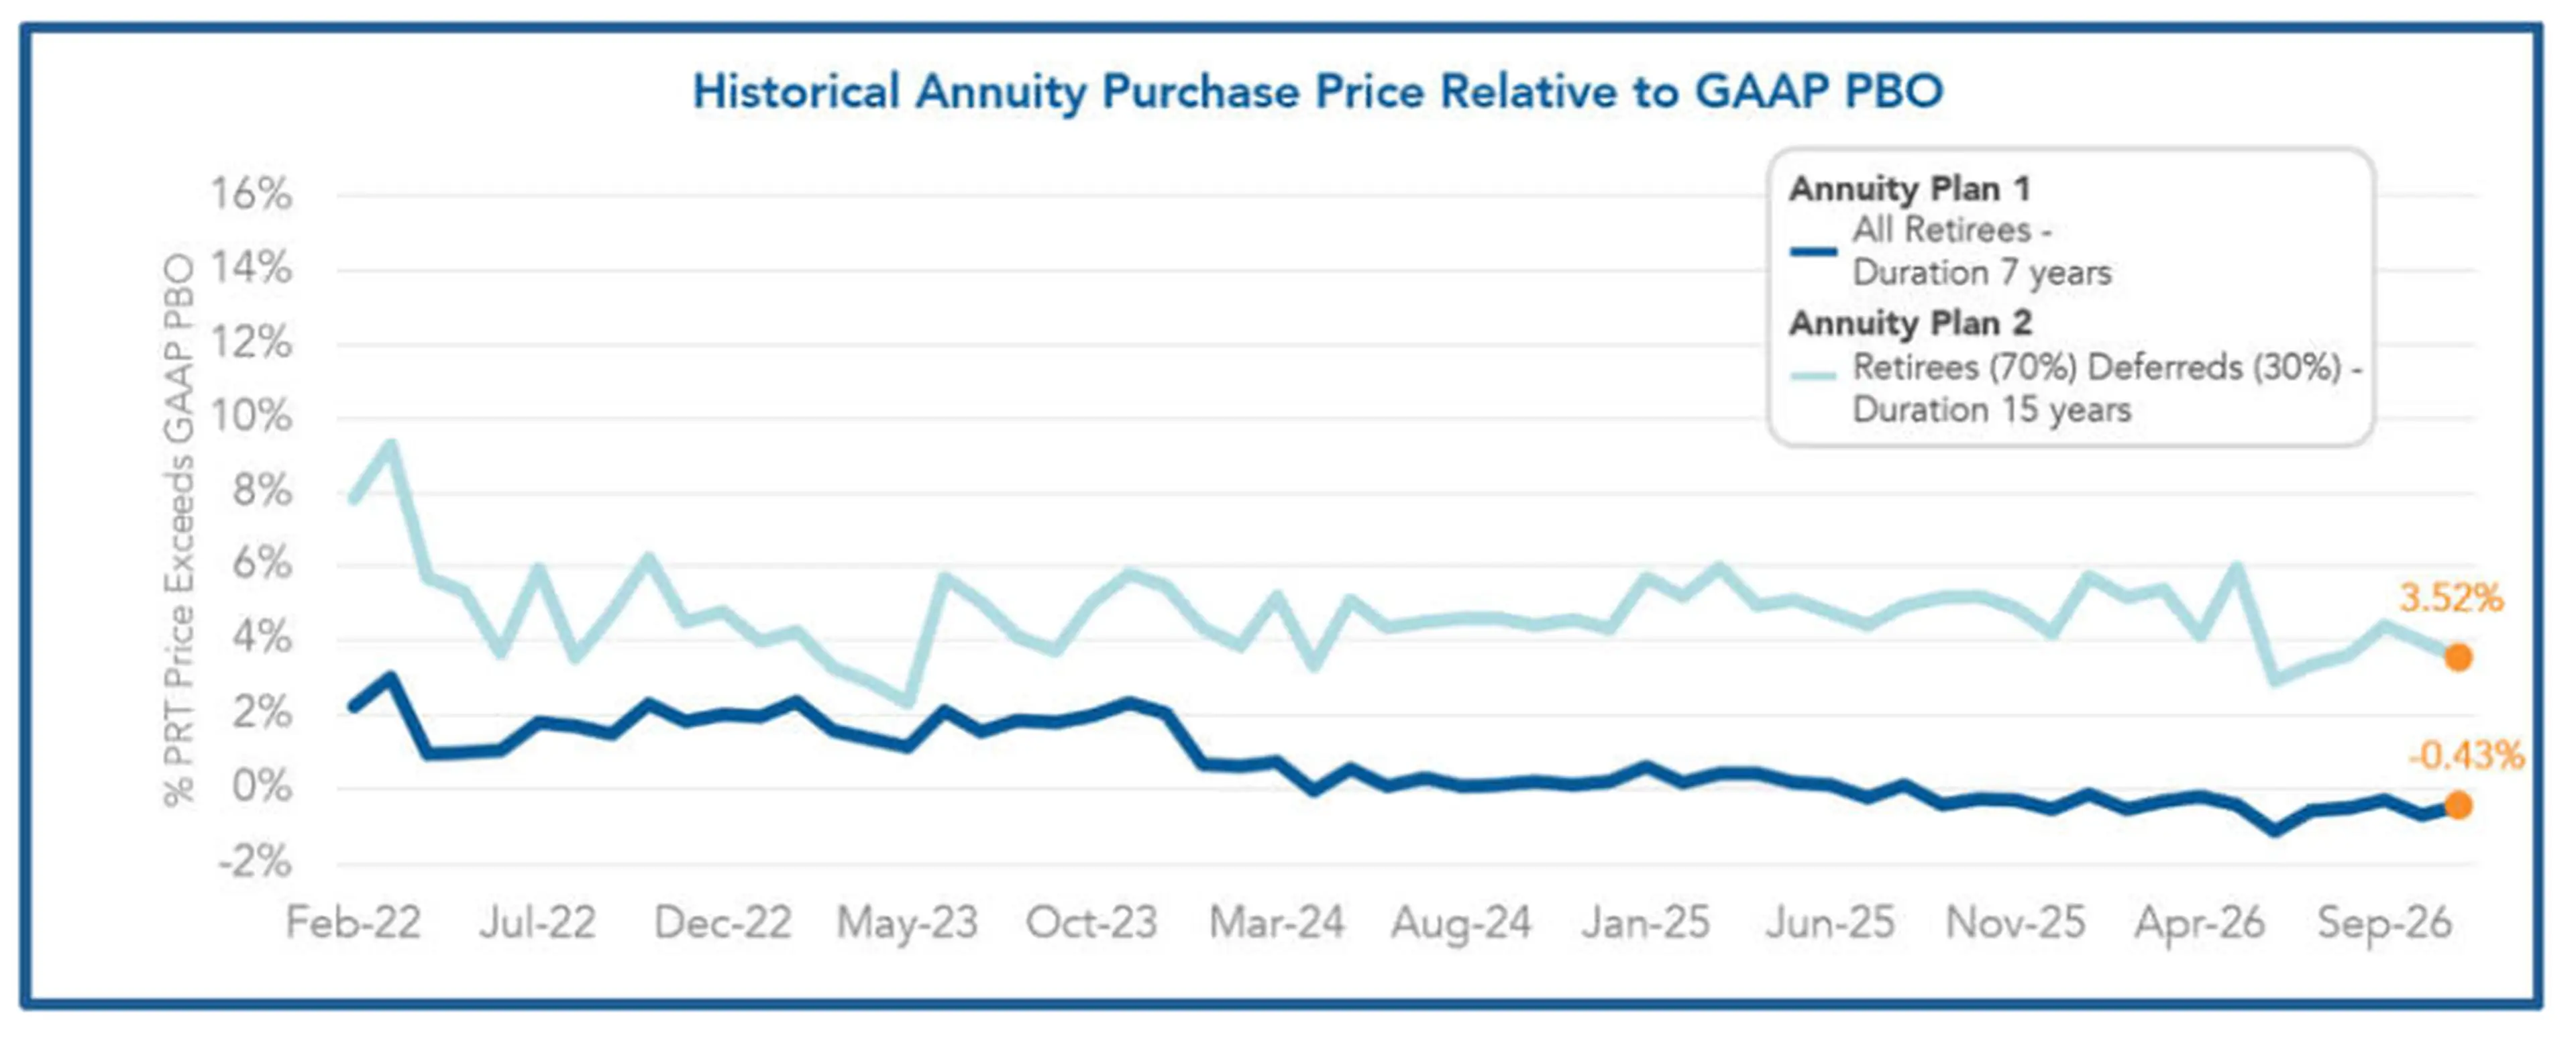
The graph below shows the spread between the annuity purchase price and the GAAP projected benefit obligation (PBO), also referred to as the accounting book value. This month, we observed Annuity Plan 1 spread at approximately 3.52% while Annuity Plan 2’s sits at -0.43%. As annuity purchase rates increase, purchase prices drop relative to the PBO. Please note that the PBO figures shown do not include future overhead costs—such as administrative expenses and PBGC premiums—that plan sponsors would incur by retaining participants in the plan.
Beyond the Midterms: Pension Risk Transfer Opportunities Remain Strong
Plan sponsors looking to derisk their defined benefit plans find themselves in essentially the same position, if not a slightly better one, than they were prior to the midterm elections. Despite the uncertainty that often surrounds an election cycle, the opportunities and objectives that plan sponsors were pursuing remain within reach. Whether the goal is to improve balance sheet certainty, transfer a portion of plan liabilities to an insurer, or move forward with a complete plan termination, the strategies available to plan sponsors have not materially changed. The current environment continues to provide an attractive opportunity for sponsors who are ready to act.
2026 has been an excellent year for pension plan terminations, and the market outlook indicates that 2027 is shaping up to be a year that could offer a similarly favorable environment. Interest rates remain elevated and plan sponsors continue to evaluate the benefits of removing pension obligations from their balance sheets, reducing administrative responsibilities, and eliminating long-term investment and longevity risks. With continued favorable market conditions and growing interest from insurers in pension risk transfer transactions, sponsors of frozen pension plans should be giving consideration to whether 2027 is the right time to complete their termination.
An important consideration that is sometimes overlooked is the time required to complete a plan termination. Most advisors will generally tell plan sponsors to expect a 12- to 18-month process from start to finish; there is an alternative. Plan termination experts can streamline the process in as little as six months while maintaining strict regulatory compliance. This difference in timing can be significant for sponsors looking to take advantage of current market conditions, meet a specific financial reporting, or a corporate objective. For plan sponsors considering termination in 2027, the time to begin evaluating the process is now. Starting early, understanding the available options, and selecting the right partners can make the difference between simply planning for termination and successfully completing it.
For additional information or inquiries about the pension risk transfer marketplace, contact Mark Unhoch: munhoch@octoberthree.com.
Submission box. If you want to see some topics covered, submit here
*October Three advises plan sponsors through every step of the Pension Risk Transfer (PRT) process. Through long established relationships with insurers in the PRT marketplace, October Three collects annuity purchase rates for Duration 7 years and Duration 15 years on a monthly basis. We have constructed 2 hypothetical annuity plans which have been valued using the latest mortality tables and mortality improvement scales. Annuity Plan 1 contains retirees only and has a liability duration of 7 years. Annuity Plan 2 contains 70% retirees and 30% deferreds and has a liability duration of 15 years. Monthly annuity rates are determined by taking the average Duration 7 and Duration 15 interest rates provided from the insurers. Annuity Plan 1 was valued using the average of the Duration 7-year interest rates collected from insurers and Annuity Plan 2 was valued using the average of the Duration 15-year interest rates collected from insurers. Using the collected annuity purchase rates and 2 hypothetical annuity plans, we have produced the following graphs representative of actual PRT market activity and the corresponding impact on pension plans.