Loading article...
September 20, 2023
Market-Based Cash Balance Plans: Key Advantages
For over a decade, professional service firms have significantly increased their adoption of Market-Based Cash Balance plans. Whether converting from an existing Fixed-Rate plan or adopting a Market-Based design from the start, nearly every new Cash Balance plan incorporates the Market-Based design. This is largely because of the advantages Market-Based Cash Balance plans offer.
In this article, we explore what makes a Market-Based plan different from other Cash Balance designs, the key advantages of a Market-Based Cash Balance plan, and the next steps for implementing these plans at your company.
How Market-Based Cash Balance Plans Work
The key difference between a Market-Based and Fixed-Rate plan is that a Market-Based Cash Balance plan is a Cash Balance plan that relies on a variable-rate interest credit, meaning the growth of the account balance is aligned with the growth of the assets directly.
Key Benefits and Differences of a Market-Based Cash Balance Plan
Market-Based Cash Balance plans offer many of the same advantages as other Cash Balance plans, including significant tax advantages and larger contribution limits. However, there are a few key differences between Market-Based plans and Fixed-Rate plans to be aware of.
| Plan Type | Market-Based | Fixed-Rate |
|---|---|---|
| Contribution Volatility | Low Volatility - stable and predictable contributions as liabilities move in tandem with plan assets, subject to certain plan limits. | High Risk - Contributions fluctuate because employers are forced to absorb the mismatch between actual investment performance and fixed liabilities. |
| Distribution Risk | Low Risk - distributions reflect actual rates of return and are aligned each year. | High Risk - distributions reflect outdated value forcing sponsor to absorb differences due when the account it valued and when it is actually paid out. |
| Allocation of Investment Performance | Direct - accounts reflect the market performance subject to cumulative return floors and caps. | Indirect - Participants get a fixed return regardless of investment performance. |
6 Benefits of a Market-Based Cash Balance Plan
1. Contribution Stability
Because actual performance on underlying plan assets (positive or negative) is credited to participant accounts, Market-Based plans rarely need to “true up” or adjust contributions at year’s end to reflect the mismatch of asset return and an internal crediting rate. In contrast, Fixed-Rate design often requires an annual adjustment as returns fail to match the plan’s stipulated rate.
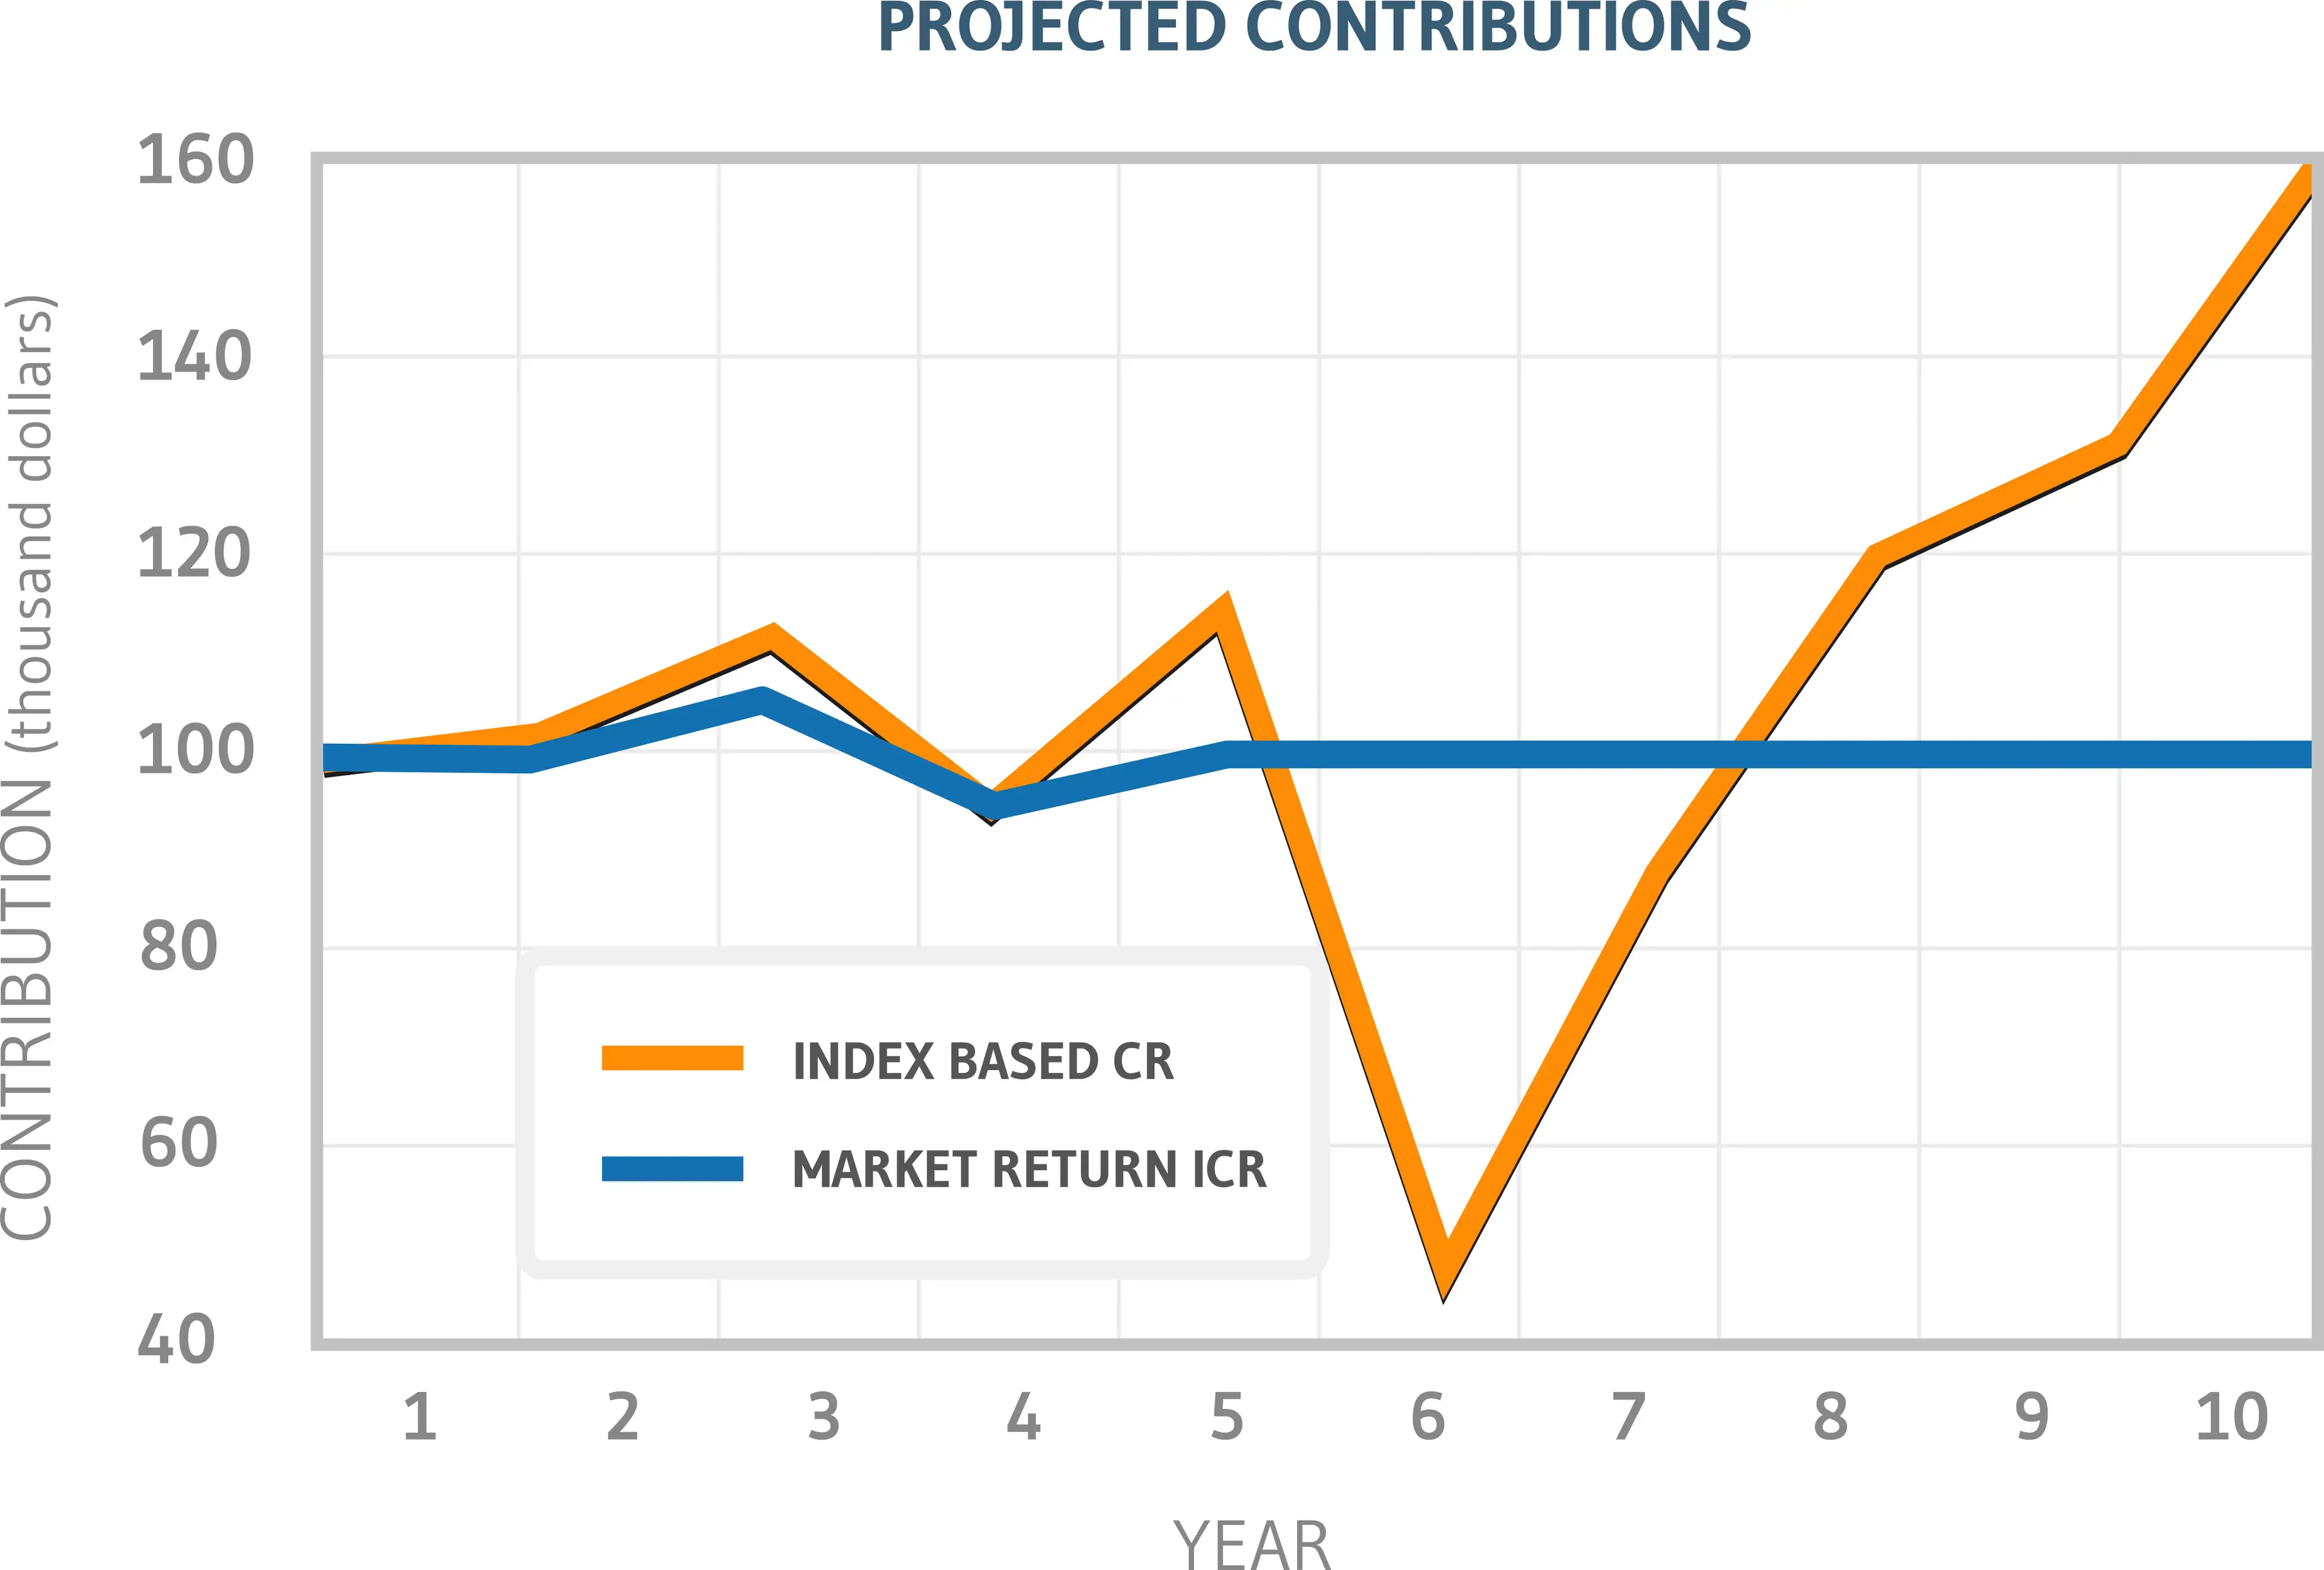
2. Reduced Exposure to Unfunded Benefits
With Market-Based plans, participant accounts (plan benefits) move directly in concert with plan assets. Therefore, it tends to remain 100% funded at all times. Fixed-Rate designs are only aligned at year’s end, so the plan can be underfunded throughout the year and can require substantial unexpected contributions during years when investment performance is sub-par, especially for those with large account balances.
3. Increased Stability as Plan Matures
Unlike every other type of Defined Benefit Plan (Traditional or Cash Balance), Market-Based plans enjoy greater stability in both contributions and funded status as plans mature. Conversely, Fixed-Rate plans become increasingly volatile over time.
4. Assets May Be Allocated to Match Risk Tolerance
Without the perceived need to target a pre-determined rate of return, Market-Based plan sponsors are free to develop an asset allocation that fits their desired risk tolerance and make appropriate adjustments over time.
5. Ability for Participants to Capture “Upside” Potential
With the investment focus taken away from achieving the low interest rate “Bogie,” long-term investment performance is typically better with a Market-Based design, which means a faster-accruing participant benefit.
6. Similarity to the 401(k) Plan Experience
Participants like being able to monitor their 401(k) account balances throughout the year. Cash Balance plans offer the same advantage, especially when valued daily through tools like October Three's Daily Platform.
Who is the Ideal Candidate for a Market-Based Cash Balance Plan?
Like other Cash Balance plans, ideal candidates are broadly individuals with consistent and high income. At October Three, clients implementing a Market-Based plan often include:
Professional services: CPAs, lawyers, doctors, IT consultants, etc.
Owner-only businesses
High earners with consistent income
Determining whether a Cash Balance plan could benefit your organization? Consider reading our article, Is Now the Time to Consider a Cash Balance Plan for Your Organization?
Considerations
This article covers the advantages of a Market-Based Cash Balance plan to demonstrate why it stands out from other Cash Balance designs. However, whether this plan type is best for your organization will depend on your unique circumstances.
For example, as a Defined Benefit plan, a Market-Based plan legally requires an actuary to certify plan funding status and calculate annual funding valuations. This added cost, the greater complexity of a Cash Balance plans and additional considerations should be discussed with a pension expert before progressing.
Get Your Free Cash Balance Illustration Today
Whether you need to reward key executives, reduce tax exposure, or boost retention with long-term wealth-building benefits, October Three can help. Request your free Cash Balance illustration today.